I find it very strange that the same sort of people who look back on the financial crisis and austerity as catalysts for great change now seem to see Brexit and Covid as catalysts for great stability.
(And the more that people attempt to deny this point the worse it gets)

More from Objective Columnist
Typically excellent piece from @dsquareddigest The exponential insight is especially neat. Think of it a little like fishing...today you can’t export oysters to the EU (because you simply aren’t allowed to), tomorrow you don’t have a fish exporting business (to the EU).
The extremely small minority of people who known anything about this who think that Brexit will be good for the City make a number of arguments which I shall address in turn...
1. They need us more than we need them. This is a variant of the German carmakers argument. And we know how that went...Business will follow the profit opportunity and if that has moved then so will the business...
And what do we mean by us / we. We’re not talking about massed ranks of Euro investing / trading etc blue blooded British institutions.
Au contraire. We’re talking about the London based subs of US, Asian and indeed European capital markets players...As soon as they think the profit opportunity has moved then so will they...it’s a market innit...
London's status as a financial centre isn't as secure as some might think | Dan Davies https://t.co/q9SU7ra4oF
— The Guardian (@guardian) February 13, 2021
The extremely small minority of people who known anything about this who think that Brexit will be good for the City make a number of arguments which I shall address in turn...
1. They need us more than we need them. This is a variant of the German carmakers argument. And we know how that went...Business will follow the profit opportunity and if that has moved then so will the business...
And what do we mean by us / we. We’re not talking about massed ranks of Euro investing / trading etc blue blooded British institutions.
Au contraire. We’re talking about the London based subs of US, Asian and indeed European capital markets players...As soon as they think the profit opportunity has moved then so will they...it’s a market innit...
A quote from this excellent piece, neatly summarising a core impact of Brexit.
The Commission’s view, according to several sources, is that Brexit means existing distribution networks and supply chains are now defunct and will have to be replaced by other systems.
Of course, this was never written on the side of a bus. And never acknowledged by government. Everything was meant to be broadly fine apart from the inevitable teething problems.
It was, however, visible from space to balanced observers. You did not have to be a trade specialist to understand that replacing the Single Market with a third country trade arrangement meant the end of many if not all of the complex arrangements optimised for the former.
In the absence of substantive mitigations, the Brexit winners are those who subscribe to some woolly notion of ‘sovereignty’ and those who did not like freedom of movement. The losers are everyone else.
But, of course, that’s not good enough. For understandable reasons Brexit was sold as a benefit not a cost. The trading benefits of freedom would far outweigh the costs. Divergence would benefit all.
The Commission’s view, according to several sources, is that Brexit means existing distribution networks and supply chains are now defunct and will have to be replaced by other systems.
Brexit reality bites: The new dawn of trade friction via @RTENews https://t.co/p6VdlhZUAN
— Tony Connelly (@tconnellyRTE) January 9, 2021
Of course, this was never written on the side of a bus. And never acknowledged by government. Everything was meant to be broadly fine apart from the inevitable teething problems.
It was, however, visible from space to balanced observers. You did not have to be a trade specialist to understand that replacing the Single Market with a third country trade arrangement meant the end of many if not all of the complex arrangements optimised for the former.
In the absence of substantive mitigations, the Brexit winners are those who subscribe to some woolly notion of ‘sovereignty’ and those who did not like freedom of movement. The losers are everyone else.
But, of course, that’s not good enough. For understandable reasons Brexit was sold as a benefit not a cost. The trading benefits of freedom would far outweigh the costs. Divergence would benefit all.
I tend to agree with this - of course many things can still go wrong...but (certainly on the UK side) as the list of outstanding issues decreases and as the cost of no deal becomes more apparent deal momentum will increase.
I find it most amusing that people invest so much value in public statements, briefings, tabloid headlines, the tweets of obscure backbenchers etc. Cherchez les fundamentals!
There is a deep vein of analytical pessimism in one particular direction, which, whether correct or not, is noteworthy. On the one hand, a firm belief in the fundamentals - gravity exists - but on the other hand those fundamentals are not meaningful to the final decision.
But gravity does exist! Whether one likes it or not. We do not have wings. Or feathers. And the realisation of the fundamentals will impact the political calculation (though timing differences may apply).
You don’t have to invest any particular optimism or see any virtue in the principal players to make this point.
Still, he's taken a very big step back now. The cliff risk was today; both sides were so close to the edge they could easily have gone over it. The fact @10DowningStreet didn't means Govt must genuinely believe there's now a landing zone that works, & which it can sell ENDS
— Mujtaba Rahman (@Mij_Europe) December 13, 2020
I find it most amusing that people invest so much value in public statements, briefings, tabloid headlines, the tweets of obscure backbenchers etc. Cherchez les fundamentals!
There is a deep vein of analytical pessimism in one particular direction, which, whether correct or not, is noteworthy. On the one hand, a firm belief in the fundamentals - gravity exists - but on the other hand those fundamentals are not meaningful to the final decision.
But gravity does exist! Whether one likes it or not. We do not have wings. Or feathers. And the realisation of the fundamentals will impact the political calculation (though timing differences may apply).
You don’t have to invest any particular optimism or see any virtue in the principal players to make this point.
More from Finance

The Dutch regulator and DNB as financial supervisor are a tough cookie to deal with. In essence they hyperregulate EU-rules into goldplated Dutch rules which go beyond what is prescribed in Europe.
All NL-customers at British banks may thus be kicked out on brexit.
Thread
/1
If we start with the capital requirements directive, it says attracting deposits is forbidden. In article 9.
https://t.co/RYl7SXligC

Now the translation of that rule into Dutch law is slightly expanded to not only prohibit attracting deposits, but to also prohibit, having those deposits under custody ('ter beschikking hebben').
That's not in EU law, but it is in our Dutch law.
https://t.co/PsbWfNY3PA

So if you wonder how this would work out for UK banks and Payment institutions servicing Dutch customers. Have a read at the technical explanation of DNB, the financial supervisor and their summarising table.
https://t.co/LL0fAnYkRJ
Passive servicing of Dutch is not allowed!

Any bank or PSP in the UK that continues to serve Dutch customers (as in retail customers, professional players are excepted) can thus be subject to fines and policing under Dutch law.
Meaning we not only have Accidental American issues in payments, but also Accidental Dutchies
All NL-customers at British banks may thus be kicked out on brexit.
Thread
/1
If we start with the capital requirements directive, it says attracting deposits is forbidden. In article 9.
https://t.co/RYl7SXligC
Now the translation of that rule into Dutch law is slightly expanded to not only prohibit attracting deposits, but to also prohibit, having those deposits under custody ('ter beschikking hebben').
That's not in EU law, but it is in our Dutch law.
https://t.co/PsbWfNY3PA
So if you wonder how this would work out for UK banks and Payment institutions servicing Dutch customers. Have a read at the technical explanation of DNB, the financial supervisor and their summarising table.
https://t.co/LL0fAnYkRJ
Passive servicing of Dutch is not allowed!
Any bank or PSP in the UK that continues to serve Dutch customers (as in retail customers, professional players are excepted) can thus be subject to fines and policing under Dutch law.
Meaning we not only have Accidental American issues in payments, but also Accidental Dutchies

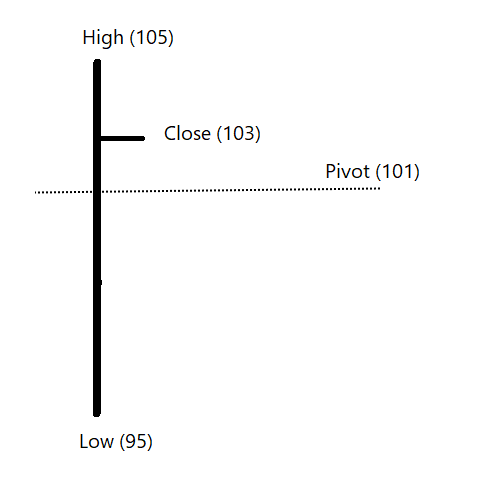




Ok here is the explanation. Grab a cup of coffee and read on. If you have not read/noticed this, you will see intraday options movement in a new light.
Say we have two options, one 50 delta ATM options and another 30 delta OTM option. Normally for a 100 point move, the ATM option will move 50 points and the OTM option will move 30 points. But in a high volatile environment, the OTM option will also move nearly 50 points
To understand why this happens, first understand why an ATM option is 50 delta. An ATM option has the probability of 50% of expiring as ITM. The price just has to close a rupee above the strike for the CE to be ITM and vice versa for PEs
Now think of a highly volatile day like today. If someone is asked where the BNF will close for the day or expiry, no one can answer. BNF can close freakin anywhere, That makes every option of an equal probability of being ITM. So all options have a 50% probability of being ITM
Hence, when a huge volatile move starts, all OTM options behave like ATM options. This phenomenon was first observed in the Black Monday crash of 1987 at Wall Street, which also gave rise to the volatility skew/smirk
In a high IV environment or when the market is very volatile
— Subhadip Nandy (@SubhadipNandy16) January 21, 2022
" OTM options will behave like ATM options", one will get almost the same delta movement
Say we have two options, one 50 delta ATM options and another 30 delta OTM option. Normally for a 100 point move, the ATM option will move 50 points and the OTM option will move 30 points. But in a high volatile environment, the OTM option will also move nearly 50 points
To understand why this happens, first understand why an ATM option is 50 delta. An ATM option has the probability of 50% of expiring as ITM. The price just has to close a rupee above the strike for the CE to be ITM and vice versa for PEs
Now think of a highly volatile day like today. If someone is asked where the BNF will close for the day or expiry, no one can answer. BNF can close freakin anywhere, That makes every option of an equal probability of being ITM. So all options have a 50% probability of being ITM
Hence, when a huge volatile move starts, all OTM options behave like ATM options. This phenomenon was first observed in the Black Monday crash of 1987 at Wall Street, which also gave rise to the volatility skew/smirk