Most feel bcoz of higher demand & lower supply but that’s nt the only factor. Imagine there is a shortage of laptops wrt the demand, but there is no liquidity in the market (people don’t have monies) will the price of laptop ⬆️? No
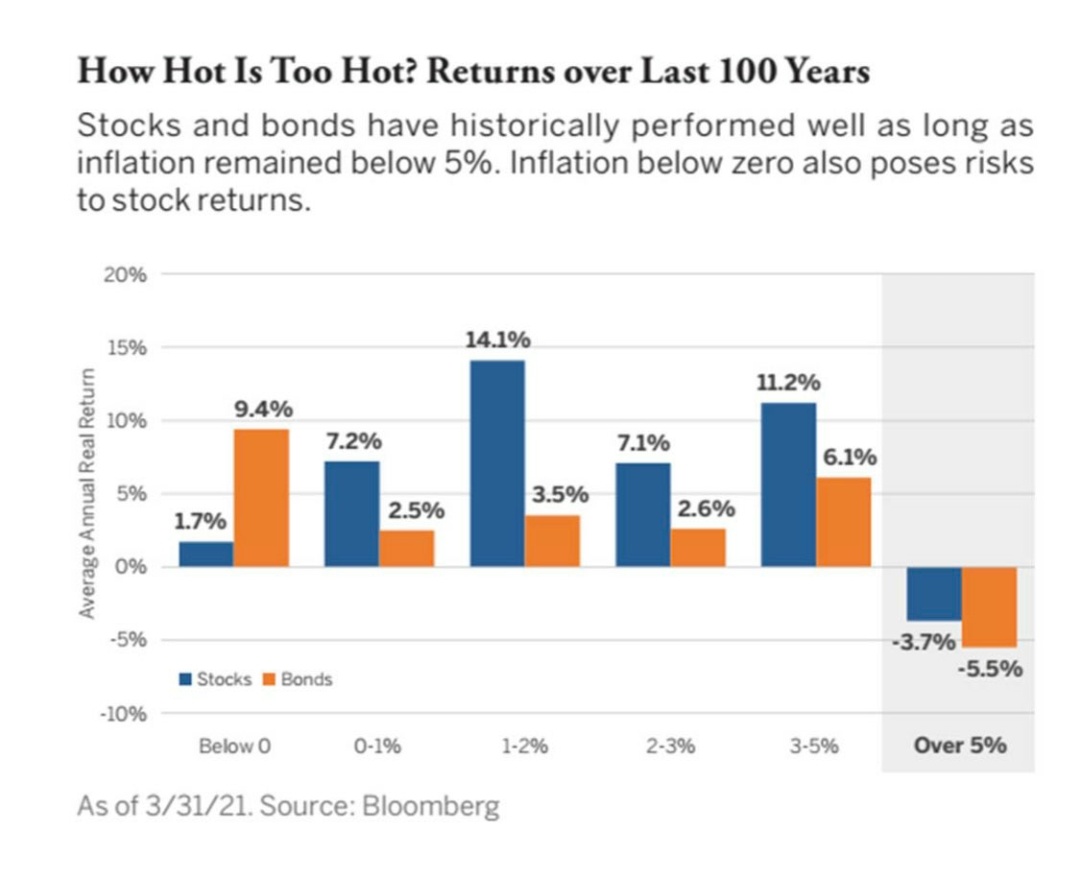
Does increase in Inflation & hence interest rates lead to a fall in equity? While theoretically yes, practically the last 20 years of data shows otherwise
Please ‘re-tweet’ 🧵& help us educate more retail investors
#Investing
Most feel bcoz of higher demand & lower supply but that’s nt the only factor. Imagine there is a shortage of laptops wrt the demand, but there is no liquidity in the market (people don’t have monies) will the price of laptop ⬆️? No
Repo rate is the rate @ which banks borrow 4m RBI. If Repo⬆️, the cost at which banks borrow is expected to ⬆️. Also the MCLR/Base rate 4 banks includes the repo rate 4 calculation & hence it is expected that if Repo ⬆️, banks will ⬆️ their lending rates. (7/n)
(b) 08-11, rates went up, equity generates 21% CAGR
(c) 2013, too small a time frame but the same reading
(d) 16-18, rates went up, equity generated 16% CAGR
#investing (14/n)
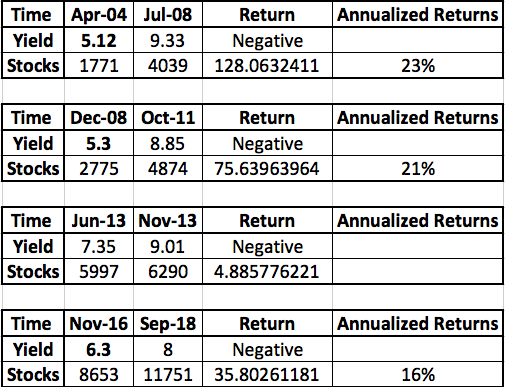
(a) In lower interest rate scenarios, corporates can raise loans at considerably low rates and redeploy it to generate higher ROCE’s till rates actually start rising much later (15/n)
#investing
Have earlier written on,
Sector Analysis - Banking, Paints, Logistic, REIT, InvIT, Sugar, Steel
- Macro
- Debt Markets
- Equity
- Gold
- Personal Finance etc.
You can find them all in the link below, https://t.co/UrRt87OLLF…… (**END**)
Here\u2019s a compilation of Personal Finance threads I have written so far. Thank you for motivating me to do it.
— Kirtan A Shah (@KirtanShahCFP) December 13, 2020
Hit the 're-tweet' and help us educated more investors
More from Kirtan A Shah


More from Finance







You May Also Like


And here they are...
THE WINNERS OF THE 24 HOUR STARTUP CHALLENGE
Remember, this money is just fun. If you launched a product (or even attempted a launch) - you did something worth MUCH more than $1,000.
#24hrstartup
The winners 👇
#10
Lattes For Change - Skip a latte and save a life.
https://t.co/M75RAirZzs
@frantzfries built a platform where you can see how skipping your morning latte could do for the world.
A great product for a great cause.
Congrats Chris on winning $250!
#9
Instaland - Create amazing landing pages for your followers.
https://t.co/5KkveJTAsy
A team project! @bpmct and @BaileyPumfleet built a tool for social media influencers to create simple "swipe up" landing pages for followers.
Really impressive for 24 hours. Congrats!
#8
SayHenlo - Chat without distractions
https://t.co/og0B7gmkW6
Built by @DaltonEdwards, it's a platform for combatting conversation overload. This product was also coded exclusively from an iPad 😲
Dalton is a beast. I'm so excited he placed in the top 10.
#7
CoderStory - Learn to code from developers across the globe!
https://t.co/86Ay6nF4AY
Built by @jesswallaceuk, the project is focused on highlighting the experience of developers and people learning to code.
I wish this existed when I learned to code! Congrats on $250!!
THE WINNERS OF THE 24 HOUR STARTUP CHALLENGE
Remember, this money is just fun. If you launched a product (or even attempted a launch) - you did something worth MUCH more than $1,000.
#24hrstartup
The winners 👇
#10
Lattes For Change - Skip a latte and save a life.
https://t.co/M75RAirZzs
@frantzfries built a platform where you can see how skipping your morning latte could do for the world.
A great product for a great cause.
Congrats Chris on winning $250!
#9
Instaland - Create amazing landing pages for your followers.
https://t.co/5KkveJTAsy
A team project! @bpmct and @BaileyPumfleet built a tool for social media influencers to create simple "swipe up" landing pages for followers.
Really impressive for 24 hours. Congrats!
#8
SayHenlo - Chat without distractions
https://t.co/og0B7gmkW6
Built by @DaltonEdwards, it's a platform for combatting conversation overload. This product was also coded exclusively from an iPad 😲
Dalton is a beast. I'm so excited he placed in the top 10.
#7
CoderStory - Learn to code from developers across the globe!
https://t.co/86Ay6nF4AY
Built by @jesswallaceuk, the project is focused on highlighting the experience of developers and people learning to code.
I wish this existed when I learned to code! Congrats on $250!!