
Ok here is the explanation. Grab a cup of coffee and read on. If you have not read/noticed this, you will see intraday options movement in a new light.
In a high IV environment or when the market is very volatile
— Subhadip Nandy (@SubhadipNandy16) January 21, 2022
" OTM options will behave like ATM options", one will get almost the same delta movement
https://t.co/3X8lCYDetq
More from Subhadip Nandy
Two year back thread on MFI, someone liked this so came up in notifications . Rather than running around 100s of indicators, I have made this my go to indicator under any circumstances and have been using this for years
This thread actually had some great answers , one can learn a lot about the thought processes of different traders from the answers. Please go thru them
What do you think/use as the most robust leading indicator if following technical analysis ? Please answer with reason , I will provide my answer after 2 hours
— Subhadip Nandy (@SubhadipNandy16) August 12, 2019
( At Delhi airport , bored as hell )
This thread actually had some great answers , one can learn a lot about the thought processes of different traders from the answers. Please go thru them


More from Finance




A 🧵on the basics of block and bulk deals.
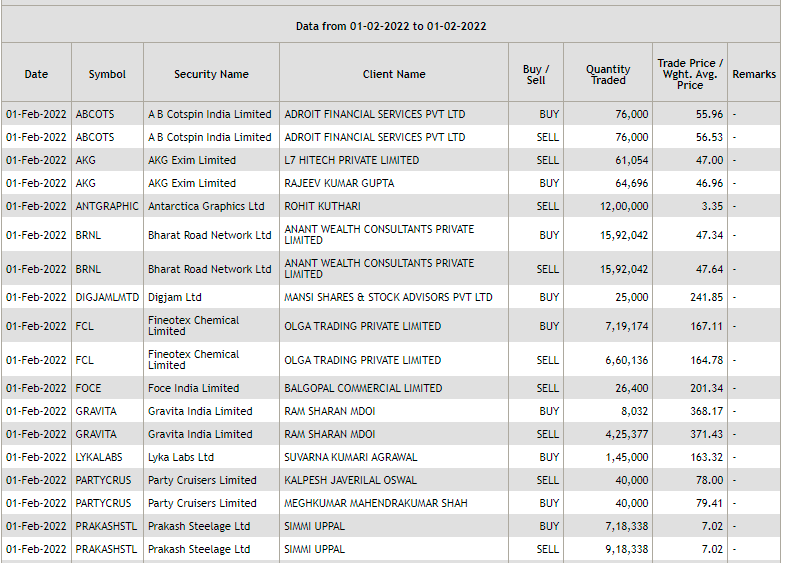
Block and bulk deals are large purchases of stocks by investment banks, mutual funds, hedge funds, pension funds, FIIs, and promoters. Tracking block and bulk deals can help give you a sense of what these large players are thinking.
A single transaction where shares more than Rs 10 crores or the number of shares traded are more than 5 lakh is considered a block deal.
Block deals are carried out in separate trading windows. This trading window operates in two shifts of 15 minutes each:
Morning trading window from 8:45 AM to 9:00 AM.
Afternoon trading window from 2:05 PM to 2:20 PM
Block deals happen in different windows to reduce volatility and sudden price movements. Given that they are traded in a separate window, they do not show up on the volume charts.
Brokers facilitating the transaction are required to inform the exchange. You can track bulk and block deals on NSE & BSE:
https://t.co/pwTyzWTnUL
https://t.co/g9BbHiEag3
Block and bulk deals are large purchases of stocks by investment banks, mutual funds, hedge funds, pension funds, FIIs, and promoters. Tracking block and bulk deals can help give you a sense of what these large players are thinking.
A single transaction where shares more than Rs 10 crores or the number of shares traded are more than 5 lakh is considered a block deal.
Block deals are carried out in separate trading windows. This trading window operates in two shifts of 15 minutes each:
Morning trading window from 8:45 AM to 9:00 AM.
Afternoon trading window from 2:05 PM to 2:20 PM
Block deals happen in different windows to reduce volatility and sudden price movements. Given that they are traded in a separate window, they do not show up on the volume charts.
Brokers facilitating the transaction are required to inform the exchange. You can track bulk and block deals on NSE & BSE:
https://t.co/pwTyzWTnUL
https://t.co/g9BbHiEag3
You May Also Like





On the occasion of youtube 20k and Twitter 70k members
A small tribute/gift to members
Screeners
technical screeners - intraday and positional both
before proceeding - i have helped you , can i ask you so that it can help someone else too
thank you
positional one
run - find #stock - draw chart - find levels
1- Stocks closing daily 2% up from 5 days
https://t.co/gTZrYY3Nht
2- Weekly breakout
https://t.co/1f4ahEolYB
3- Breakouts in short term
https://t.co/BI4h0CdgO2
4- Bullish from last 5
intraday screeners
5- 15 minute Stock Breakouts
https://t.co/9eAo82iuNv
6- Intraday Buying seen in the past 15 minutes
https://t.co/XqAJKhLB5G
7- Stocks trading near day's high on 5 min chart with volume BO intraday
https://t.co/flHmm6QXmo
Thank you