Thank you for participating!
Goodnight 💤
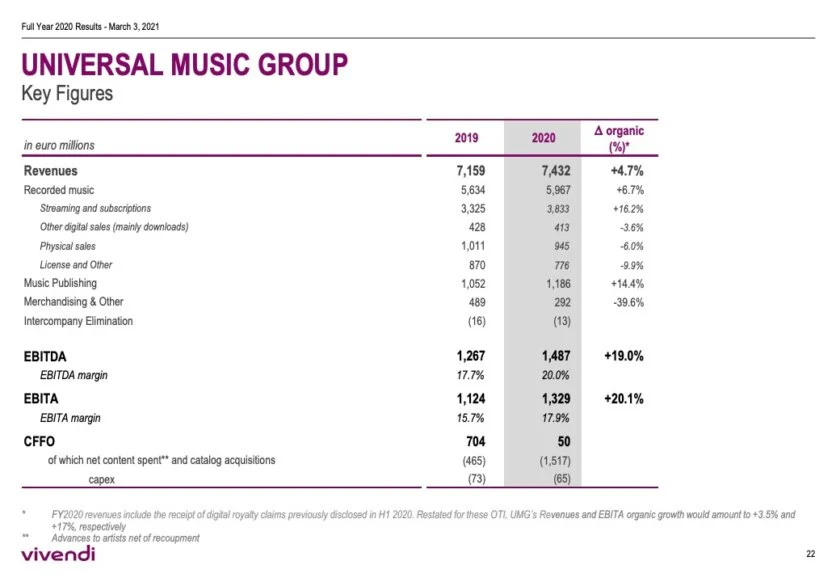
Homework for all the interested participants here:
— Intrinsic Compounding (@soicfinance) June 27, 2021
Q1.Why 20% and not 50%+ Margins for UMG
Q2. Differences in dynamics between Western&Indian cos?
Q3. Trends in West vs Trends in India in the industry.
Research and find the answers. My job is done \U0001f601\U0001f64f
If you see the ebitda of universal music its low 20% compared to our saregama 30% or tips 50%. So when you compare earnings saregama is 40x and tips is 30x and universal music is 30x. Also these type of companies are less( low or no capex with excellent and growinh cashflows)
— Srikanth V (@mynameisnani75) June 27, 2021
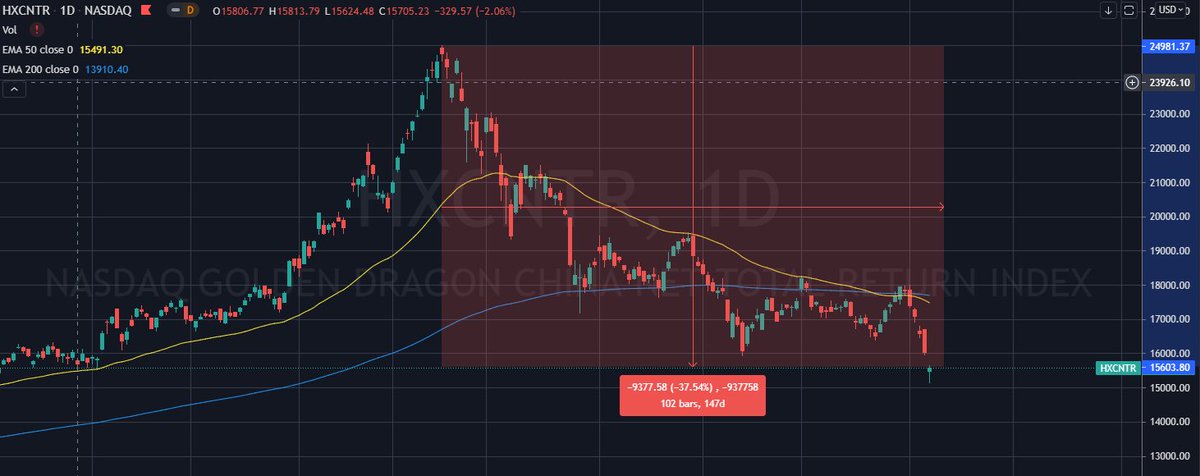
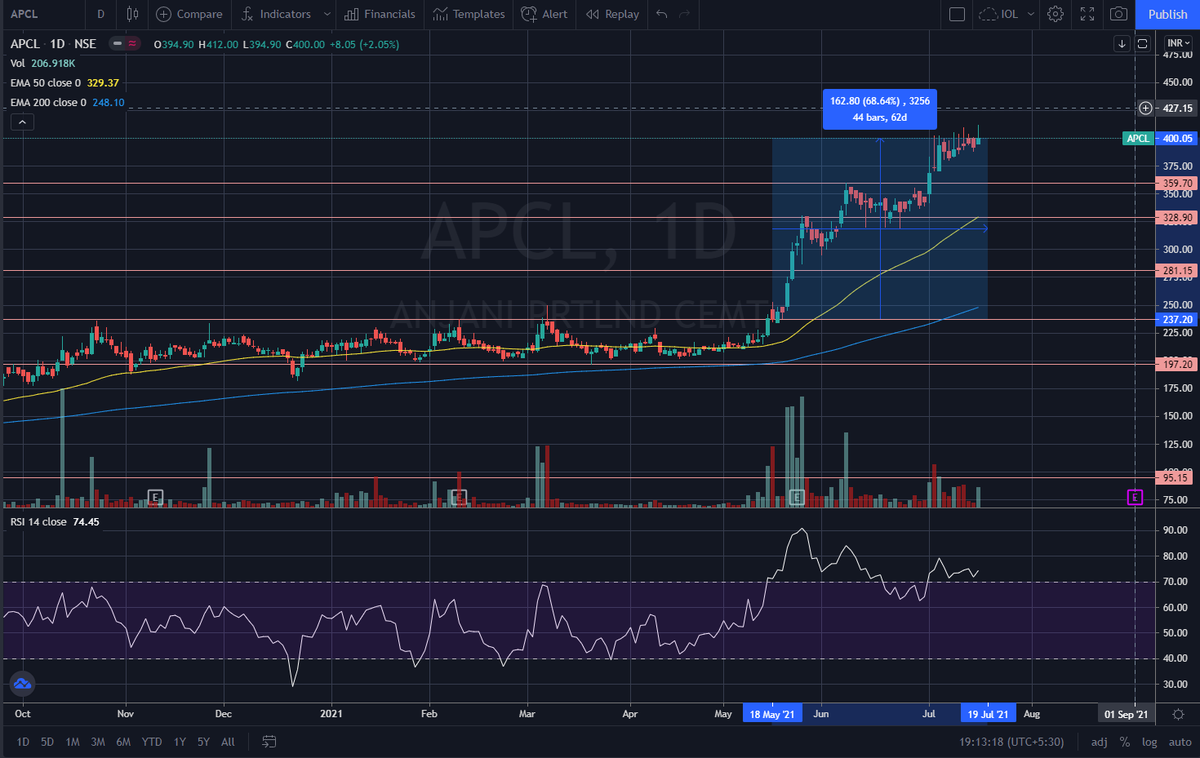
@drprashantmish6 @Investor_Mohit
— Arun Choudhary FCA (@YOUNGBRUJ) July 9, 2021
1) Information on cement sector in India
India at 550 MTPA is the 2nd largest cement producer globally. Expected to move to 650 MTPA by 2025E pic.twitter.com/GqtcSk03TU
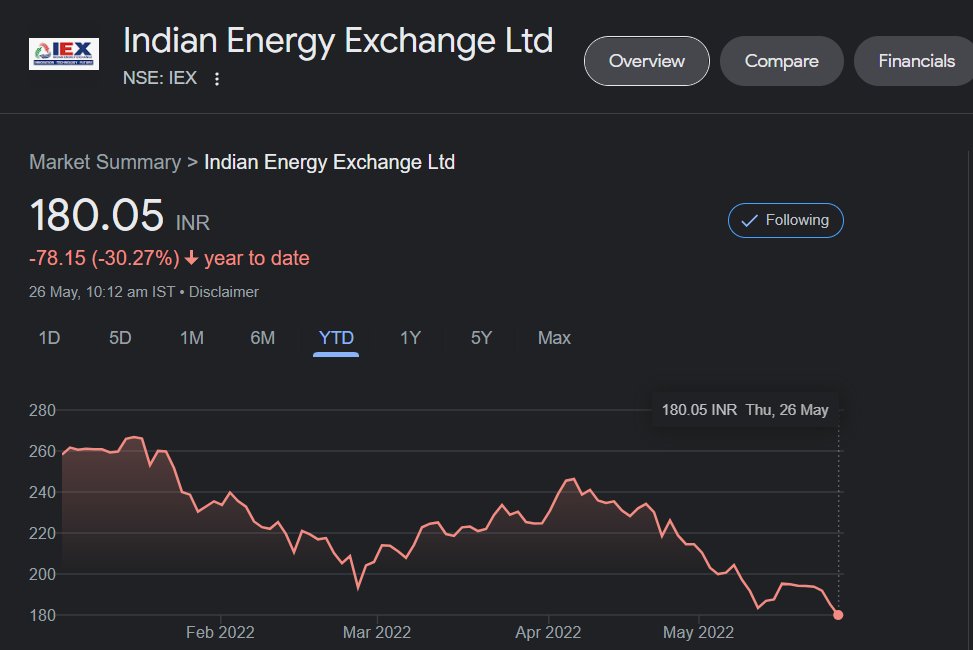
#IEX in my PF is a giant growing dividend paying Gorilla
— Tar \u26a1 (@itsTarH) October 18, 2021
Main reason I don't mess around with my holdings is cause I expect it to.
Pay Dividend = to my investment within the next decade
Glad they are considering Bonus Issue (tax favorable) instead of Cash Dividend. pic.twitter.com/2cLt6yK0Xw