Key Highlights from the Union Budget 2021, as presented by the Hon’ble Finance Minister.

Direct Taxes -
• Vivad Se Viswas Scheme Last Date of filing extended to 28th February 2021.
• Citizens of age 75 years and above who have only Pension and Interest income – Need not file👇

Income Tax Returns
• Re-opening of Assessment to reduced to 3 years from 6 years. Only where evidence of concealment of income of Rs. 50 lakhs or more – re-opening can be made up to 10 years & only with the approval of Pr.CCIT.
👇
• Reducing Litigation for small taxpayers – Constitution of Faceless Dispute Resolution Panel for people with Total Income up to Rs.50 lakh and disputed income of Rs.10 lakh
• Income Tax Appellate Tribunal to become Faceless – Only electronic communication will be done
👇
• Relaxation to NRIs – Rules to remove hardship of Double Taxation
• Tax Audit Limit to be increased to Rs.10 crores from Rs.5 crores for those having less than 5% cash transactions
• Dividend Tax- Dividend will be exempt from TDS. Advance tax liability on dividend income
👇
will arise only after the declaration or payment of the dividend. For Foreign Investors – a lower treaty rate benefit will be given.
• Affordable Housing – Additional Interest deduction (Sec 80EEA) of Rs.1.5 lakhs to be extended for loans taken till 31st March 2022.
👇
• Affordable Housing Projects – Tax Holiday extended till 31st March 2022.
• Tax Holiday for Capital Gains for Aircraft Leasing Companies and Tax Exemption to Lease paid to Foreign Persons
• Pre-Filling of Returns – Details of Capital Gains, Dividend Income and Interest
👇
income will be pre-filled in the returns
• Relief to Trusts – Charitable trusts running Hospitals and Educational Institutions relief increased from Rs.1 crore to Rs.5 crore.
• Employee contribution not paid by the employer will not be allowed as a deduction.
👇
• Tax holiday for Start-Ups extended to 31st March 2022. Capital Gains exemption on investment in startups also extended to 31s March 2022.

MCA, Companies Act, LLP Act
• Easing Compliance requirements of Small Companies – Threshold increased to Share Capital increased
👇
up to Rs.2 crore and Turnover up to Rs.20 crore will be Small Companies
• Allow One Person Companies (OPC) to grow without any restriction in Share Capital or Turnover. NRIs will be allowed to set-up OPCs. Presence in India of 120 days in a year enough to start an OPC.
👇
• Launching MCA Version 3.0 – E-Scrutiny, E-Adjudication, and Compliance management to be simplified.
• Decriminalisation of LLP Act, 2008
• Tribunals to be rationalized.

#WA 🙏

More from Economy

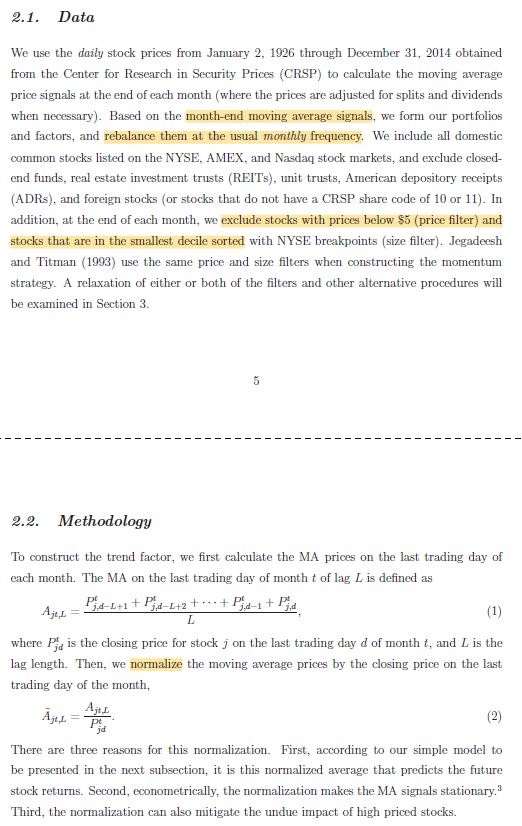
1/ Trend Factor: Any Economic Gains from Using Information over Investment Horizons? (Han, Zhou, Zhu)

"A trend factor using multiple time lengths outperforms ST reversal, momentum, and LT reversal, which are based on the three price trends separately."

https://t.co/udkvsdw2Lz


2/ This resembles combining multiple measures of ST reversal, momentum, and LT reversal (forecasts determined by walking forward rather than using signs from the full sample).

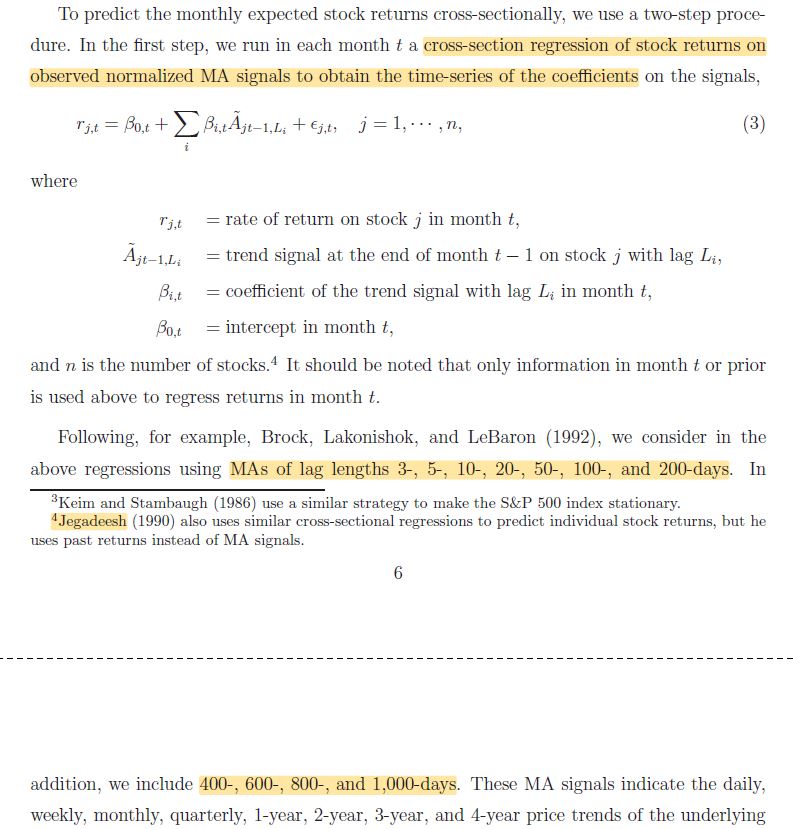
Unlike normal moving average signals, these are *cross-sectional.* More below:
https://t.co/wkIFLg9jtK


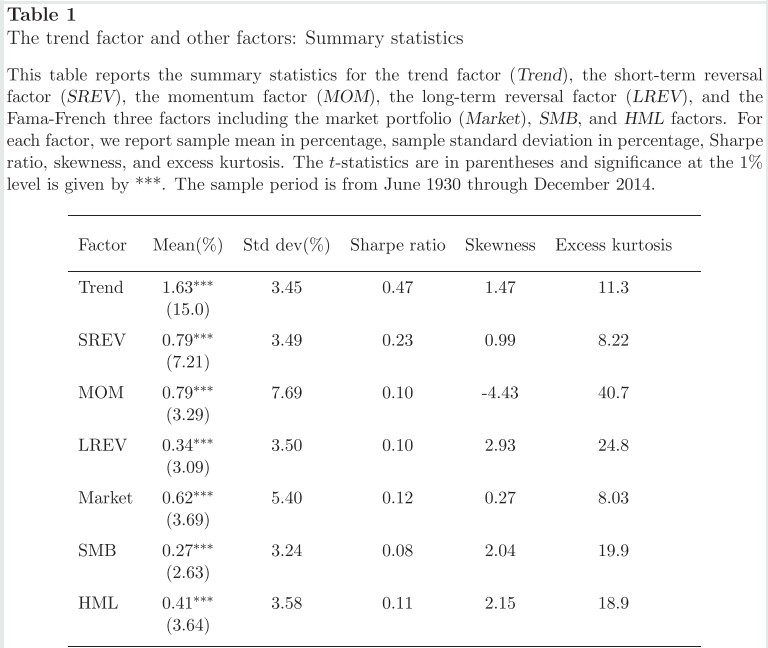
3/ Unsurprisingly, the Trend factor formed by this approach outperforms benchmarks in terms of both Sharpe ratio and tail metrics. It's combining momentum with two factors that are negatively correlated to it AND using multiple specifications.

More here:
https://t.co/x8Tloz3iyL


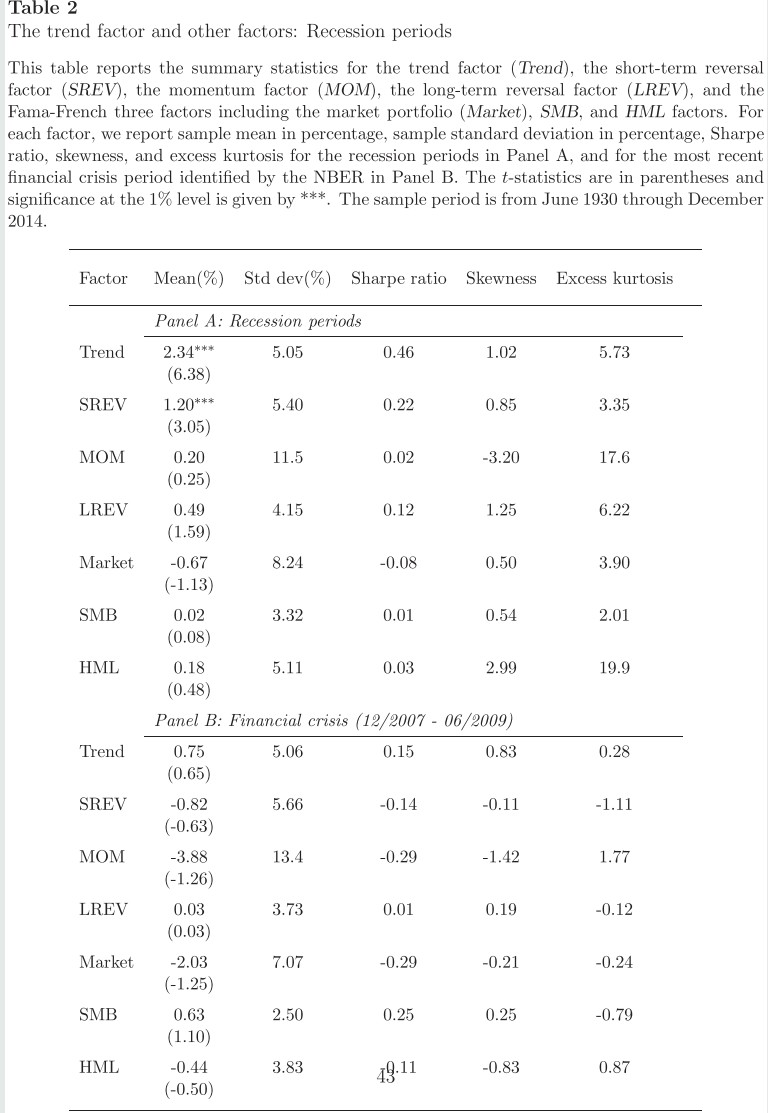
4/ "Average return and volatility of the trend factor are both higher in recession periods. However, the Sharpe ratio is virtually the same.

"Interestingly, all of the factors still have positive average returns.

"Momentum experiences the greatest increase in volatility."


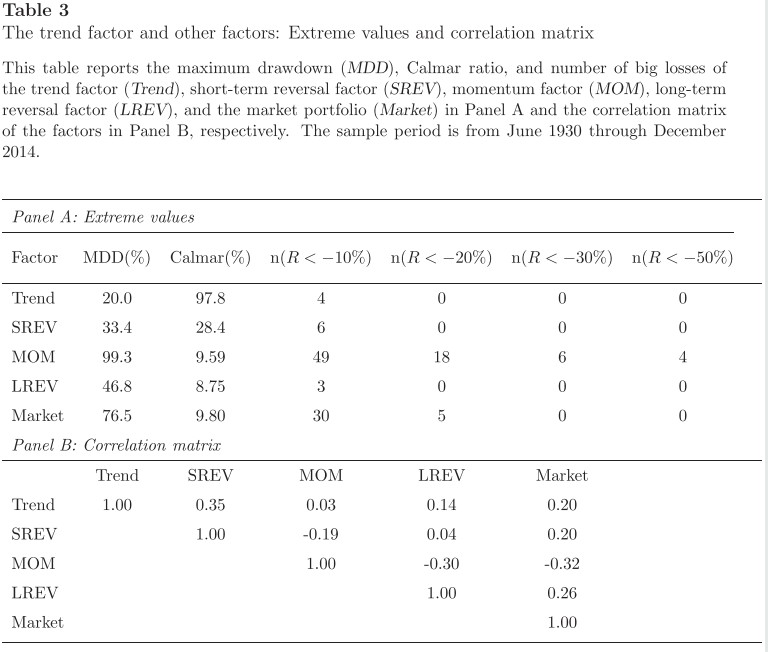
5/ "In terms of maximum drawdown and the Calmar ratio, the trend factor performs the best.

"The trend factor is correlated with the short-term reversal factor (35%), long-term reversal factor (14%), and the market (20%) but is virtually uncorrelated with the momentum factor."

You May Also Like