The Art of asking smart questions | When do you really graduate as an investor?
Time for a thread🧵🧵🧵🧵🧵
Retweet for Max reach!!

Another example that comes to mind is Balkrishna Industries vs other tyre players.🚜🚜
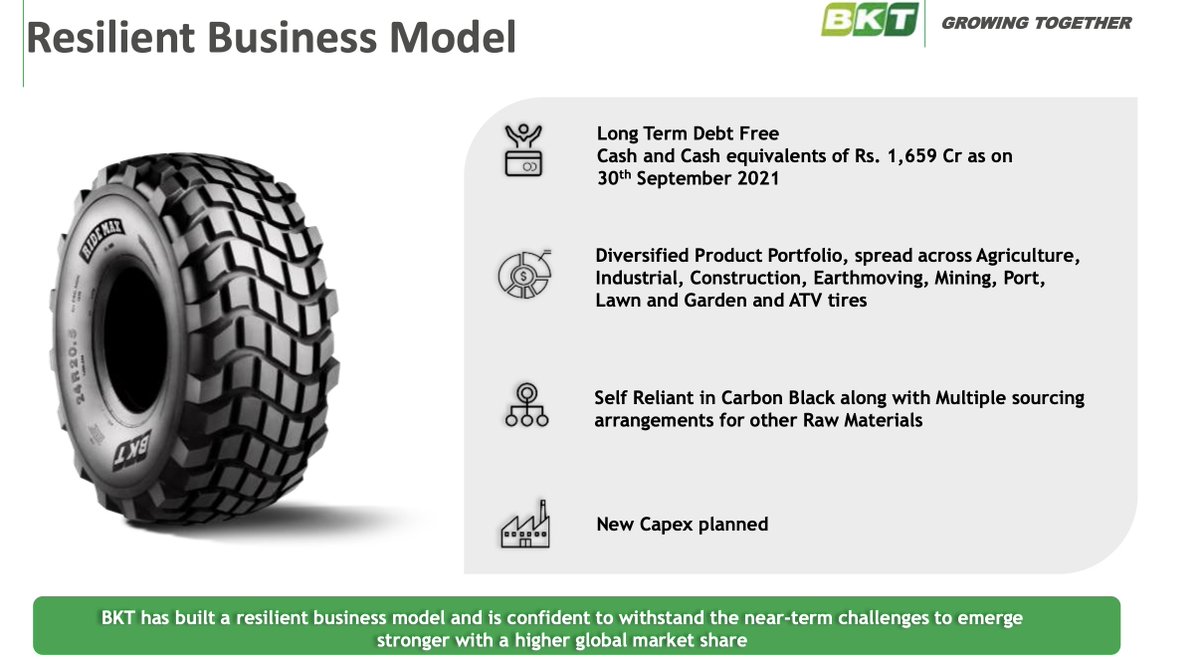
If they do this successfully, this will become a much more stable and structural business, thereby killing the shallow cyclicality in margins permanently.

Your real graduation as an investor comes when you do 2-3 steps deeper than plain vanilla analysis.
Always start with why and think about the second and third order consequences.
PI Industries has been trying to get into the pharma adjacency since early 2013. Yet, they haven’t been able to do it.
The company recently raised equity and even tried to acquire IndSwift Labs.
Size of the market for Agro CRAMS is $6 Billion and PI is already doing almost 4000 crores (saturated market?) of sales.
Stock will remain in consolidation range in my view, till the business is able to digest a Pharma asset and deliver earnings.
First order consequence:- Free cash flow generation reduces
2nd order consequence:- Depreciation increases,
3rd order consequence PAT growth🔽🔽
Final consequence, ROCE takes a dip. Always start with Why and then what (post an action)
In 2016 Deepak Announced this mammoth capex for a Phenol plant, lets see what they wrote in the annual report:-
A major contribution from phenol segment would be in offering a range
Ever since then the game plan was clear if you read between the lines,
First Part=Bulk chemicals i.e. import substitution = x
More from Intrinsic Compounding

More from All

https://t.co/6cRR2B3jBE
Viruses and other pathogens are often studied as stand-alone entities, despite that, in nature, they mostly live in multispecies associations called biofilms—both externally and within the host.
https://t.co/FBfXhUrH5d

Microorganisms in biofilms are enclosed by an extracellular matrix that confers protection and improves survival. Previous studies have shown that viruses can secondarily colonize preexisting biofilms, and viral biofilms have also been described.

...we raise the perspective that CoVs can persistently infect bats due to their association with biofilm structures. This phenomenon potentially provides an optimal environment for nonpathogenic & well-adapted viruses to interact with the host, as well as for viral recombination.

Biofilms can also enhance virion viability in extracellular environments, such as on fomites and in aquatic sediments, allowing viral persistence and dissemination.

Viruses and other pathogens are often studied as stand-alone entities, despite that, in nature, they mostly live in multispecies associations called biofilms—both externally and within the host.
https://t.co/FBfXhUrH5d
Microorganisms in biofilms are enclosed by an extracellular matrix that confers protection and improves survival. Previous studies have shown that viruses can secondarily colonize preexisting biofilms, and viral biofilms have also been described.
...we raise the perspective that CoVs can persistently infect bats due to their association with biofilm structures. This phenomenon potentially provides an optimal environment for nonpathogenic & well-adapted viruses to interact with the host, as well as for viral recombination.
Biofilms can also enhance virion viability in extracellular environments, such as on fomites and in aquatic sediments, allowing viral persistence and dissemination.




1. Mini Thread on Conflicts of Interest involving the authors of the Nature Toilet Paper:
https://t.co/VUYbsKGncx
Kristian G. Andersen
Andrew Rambaut
Ian Lipkin
Edward C. Holmes
Robert F. Garry
2. Thanks to @newboxer007 for forwarding the link to the research by an Australian in Taiwan (not on
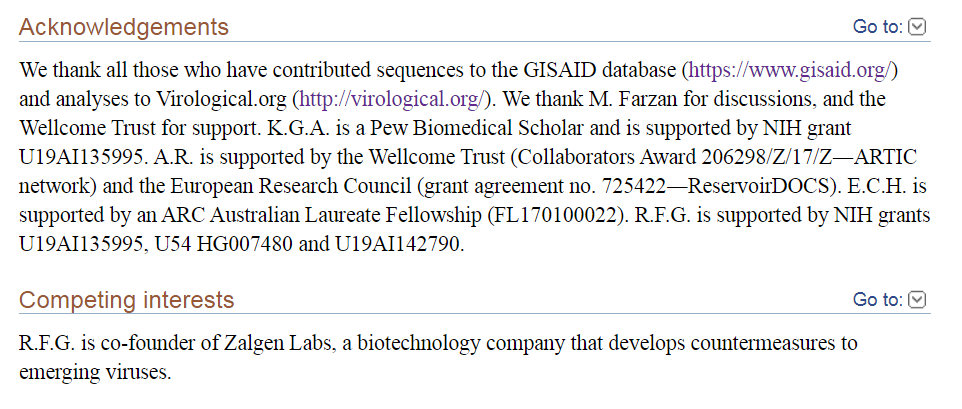
3. K.Andersen didn't mention "competing interests"
Only Garry listed Zalgen Labs, which we will look at later.
In acknowledgements, Michael Farzan, Wellcome Trust, NIH, ERC & ARC are mentioned.
Author affiliations listed as usual.
Note the 328 Citations!
https://t.co/nmOeohM89Q
4. Kristian Andersen (1)
Andersen worked with USAMRIID & Fort Detrick scientists on research, with Robert Garry, Jens Kuhn & Sina Bavari among
5. Kristian Andersen (2)
Works at Scripps Research Institute, which WAS in serious financial trouble, haemorrhaging 20 million $ a year.
But just when the first virus cases were emerging, they received great news.
They issued a press release dated November 27, 2019:
https://t.co/VUYbsKGncx
Kristian G. Andersen
Andrew Rambaut
Ian Lipkin
Edward C. Holmes
Robert F. Garry
2. Thanks to @newboxer007 for forwarding the link to the research by an Australian in Taiwan (not on
3. K.Andersen didn't mention "competing interests"
Only Garry listed Zalgen Labs, which we will look at later.
In acknowledgements, Michael Farzan, Wellcome Trust, NIH, ERC & ARC are mentioned.
Author affiliations listed as usual.
Note the 328 Citations!
https://t.co/nmOeohM89Q
4. Kristian Andersen (1)
Andersen worked with USAMRIID & Fort Detrick scientists on research, with Robert Garry, Jens Kuhn & Sina Bavari among
Our Hans Kristian Andersen working with Jens H. Kuhn, Sina Bavari, Robert F. Garry, Stuart T. Nichol,Gustavo Palacios, Sheli R. Radoshitzky from USAMRIID and Fort Detrick to tell more fairy tales? Full emails listed for queries...https://t.co/kLRoQTxiGD pic.twitter.com/uHNuGraPP2
— Billy Bostickson \U0001f3f4\U0001f441&\U0001f441 \U0001f193 (@BillyBostickson) August 26, 2020
5. Kristian Andersen (2)
Works at Scripps Research Institute, which WAS in serious financial trouble, haemorrhaging 20 million $ a year.
But just when the first virus cases were emerging, they received great news.
They issued a press release dated November 27, 2019: