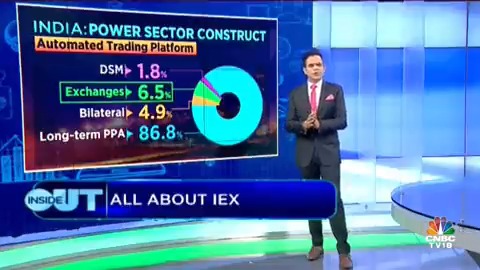
120: It's just a power exchange
250: Electricity in India won't grow
300: It just makes 4paise per trade
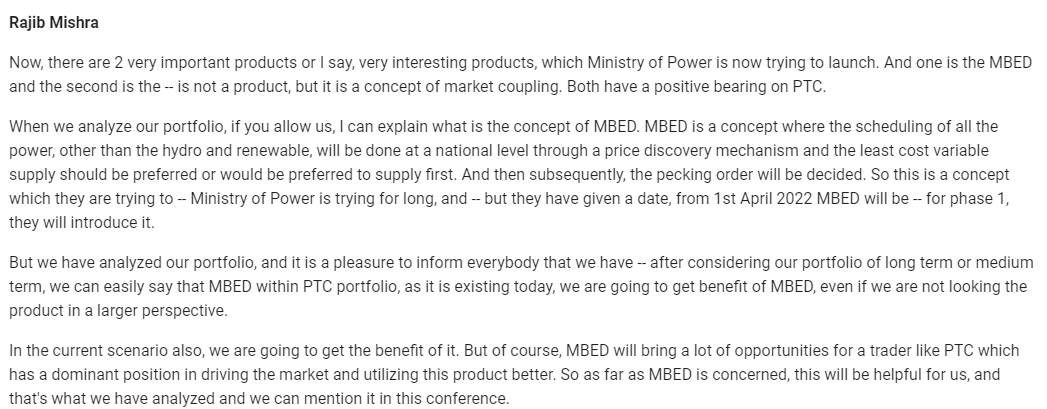
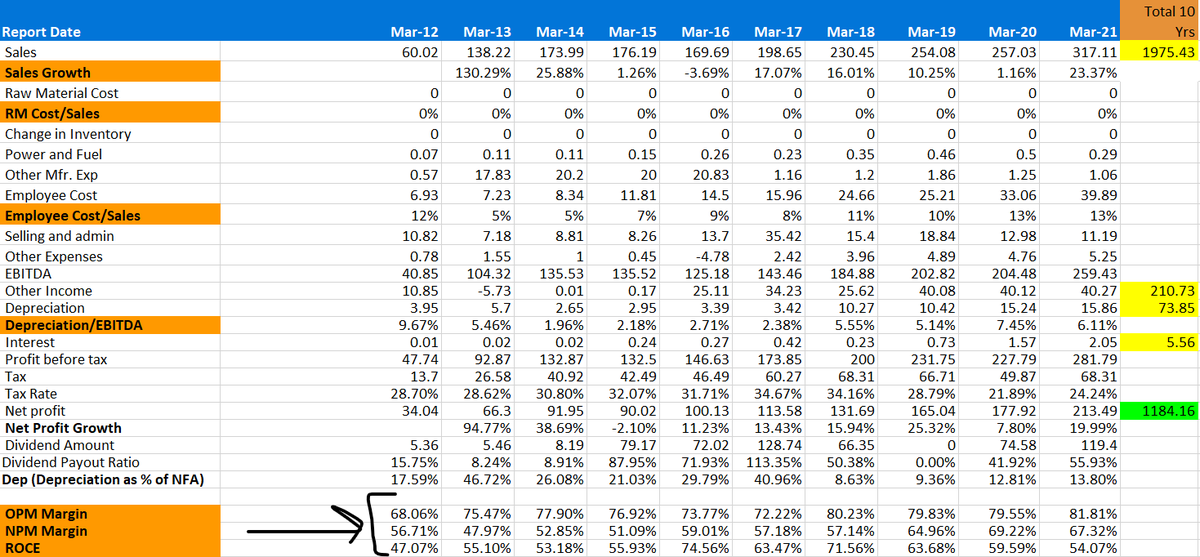
350: MBED will erode it's profitablilty
500: Maybe what @itsTarH said about IEX = NSE + Zerodha was right
570: Buys IEX
#JourneyOfAPessimist
Zerodha + NSE = IEX \U0001f4a1\u26a1\ufe0f
— Tar \u26a1 (@itsTarH) June 20, 2021
More from Tar ⚡


ROCE 1 Yr: 32.7%
ROCE 3 Yr: 24.8%
ROE: 27.4%
ROE 3 Yr: 19%
Op Margin: 28.4%
Reserves: 32% of Current Market Cap
Debt: Nil
Profit CAGR 3Yrs: 54%
Debtor Days: 15
Inventory Turnover > 5
CFO YoY Increase : 160%
Some of you got it correct. Its Anjali Portland.
The company just acquired another cement company that will double the total sales immediately.
https://t.co/2xVnpJapPy
The acquisition was financed by adding debt, so interest costs from next quarter will go up but still great!
For a company that operates in a cyclical sector like cement!
What I liked is that the company was able to maintain the balance sheet and margins even in a down cycle.
With real estate sector reviving, this can be a great bet from here.
No recommendations, just an observation.
Market started re-rating the stock as soon as they announced acquisition.
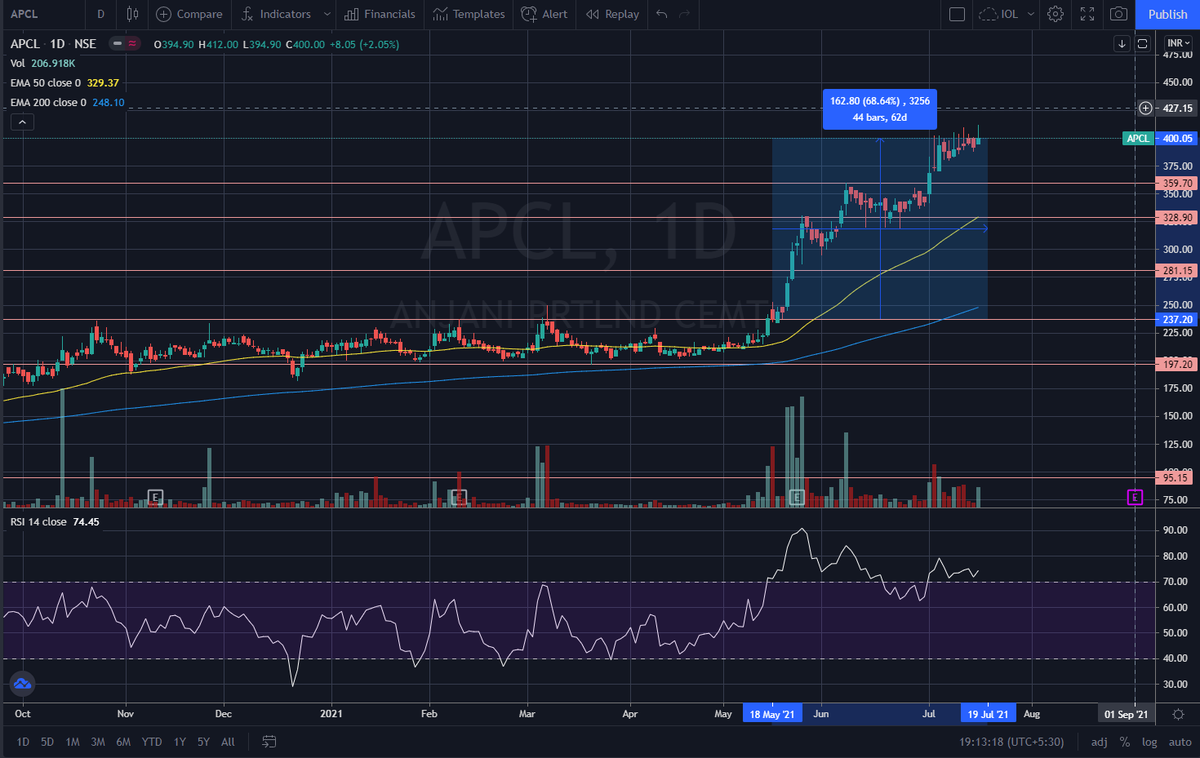
Someone did some work on details of acquisition, sharing the thread
@drprashantmish6 @Investor_Mohit
— Arun Choudhary FCA (@YOUNGBRUJ) July 9, 2021
1) Information on cement sector in India
India at 550 MTPA is the 2nd largest cement producer globally. Expected to move to 650 MTPA by 2025E pic.twitter.com/GqtcSk03TU
Already broken it's support at 200 today, can fall more on this event. https://t.co/jwqUwbUOXE
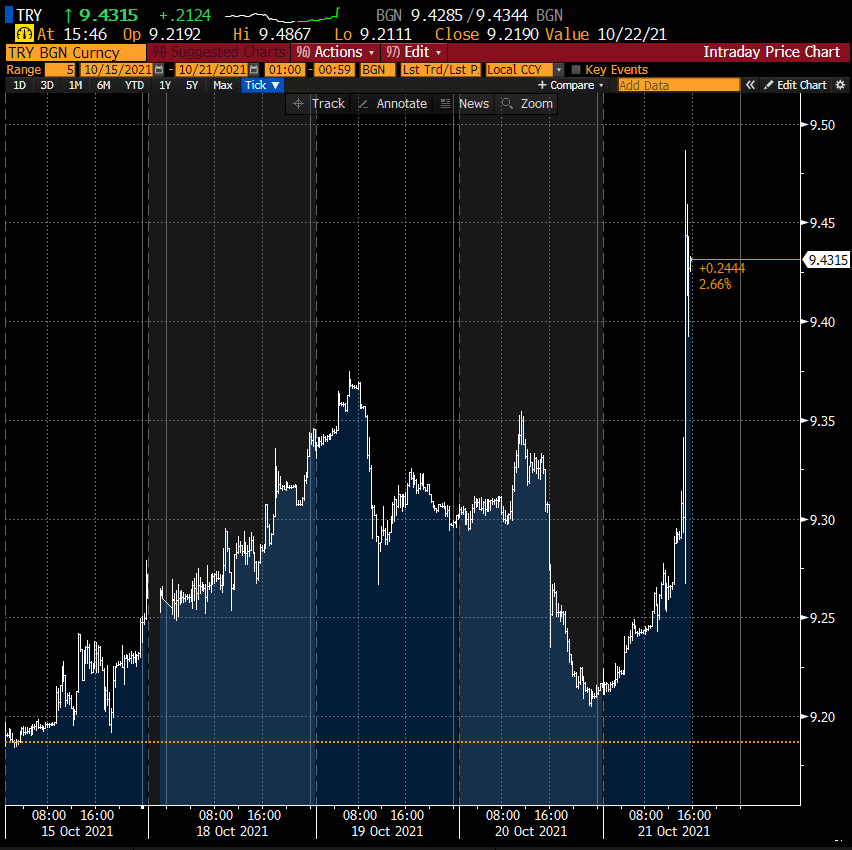
BREAKING: The Turkish lira falls to a record low after the central bank cut its interest rate for a second meeting in a row https://t.co/Sf4rfoo7Cz pic.twitter.com/2YM1Sh5DIU
— Bloomberg (@business) October 21, 2021
More from Iexinfo

While the market size may grow a lot in the next decade, the government policy risk still stays.
Pic 1: PTC Q4FY21 call
Pic 2: PTC Q1FY22 call
https://t.co/eImnTNEZeX
Long term investing is a peaceful & slow way of creating wealth.And sometime luck plays its role too.
— SmartSyncServices.com (@SmartSyncServ) September 1, 2021
When we researched IEX in 2019 & recommended investors to buy in Mar 2020, we never anticipated such high growth & 470%+ rise in 1.5 Yrs.@MashraniVivekhttps://t.co/qZIdI10ybc pic.twitter.com/v4UYa6fRyn




You May Also Like


As someone\u2019s who\u2019s read the book, this review strikes me as tremendously unfair. It mostly faults Adler for not writing the book the reviewer wishes he had! https://t.co/pqpt5Ziivj
— Teresa M. Bejan (@tmbejan) January 12, 2021
The meat of the criticism is that the history Adler gives is insufficiently critical. Adler describes a few figures who had a great influence on how the modern US university was formed. It's certainly critical: it focuses on the social Darwinism of these figures. 2/x
Other insinuations and suggestions in the review seem wildly off the mark, distorted, or inappropriate-- for example, that the book is clickbaity (it is scholarly) or conservative (hardly) or connected to the events at the Capitol (give me a break). 3/x
The core question: in what sense is classics inherently racist? Classics is old. On Adler's account, it begins in ancient Rome and is revived in the Renaissance. Slavery (Christiansen's primary concern) is also very old. Let's say classics is an education for slaveowners. 4/x
It's worth remembering that literacy itself is elite throughout most of this history. Literacy is, then, also the education of slaveowners. We can honor oral and musical traditions without denying that literacy is, generally, good. 5/x