
You have been having your best production yields you have ever had; you have been building your credit up and are now financing your own electrically powered irrigation pump that has much better access to water due to larger irrigation installments upstream.
(26/50)
With FDI inflows increasing, the GoE begins hiring engineers, irrigation technique counselors, contracting out developers and suppliers and restructures Kamali’s current irrigation channel.
Let’s enter back into Kamali’s world:
You have been having your best production yields you have ever had; you have been building your credit up and are now financing your own electrically powered irrigation pump that has much better access to water due to larger irrigation installments upstream.
You are now able to expand the amount of wheat coverage from .5 hectares to all 1.75 hectares that you own, but that means your input costs will increase by 250%. The financial institutions aren't yet comfortable issuing an unsecured credit voucher to you of that size.
Your alternative is to outsource a loan from the current Web 2 CeFi infrastructure via mobile app, Opay, a borrow/lending platform in Ethiopia. Opay was demanded to be taken off of Google Play Store for predatory lending as their practices included:
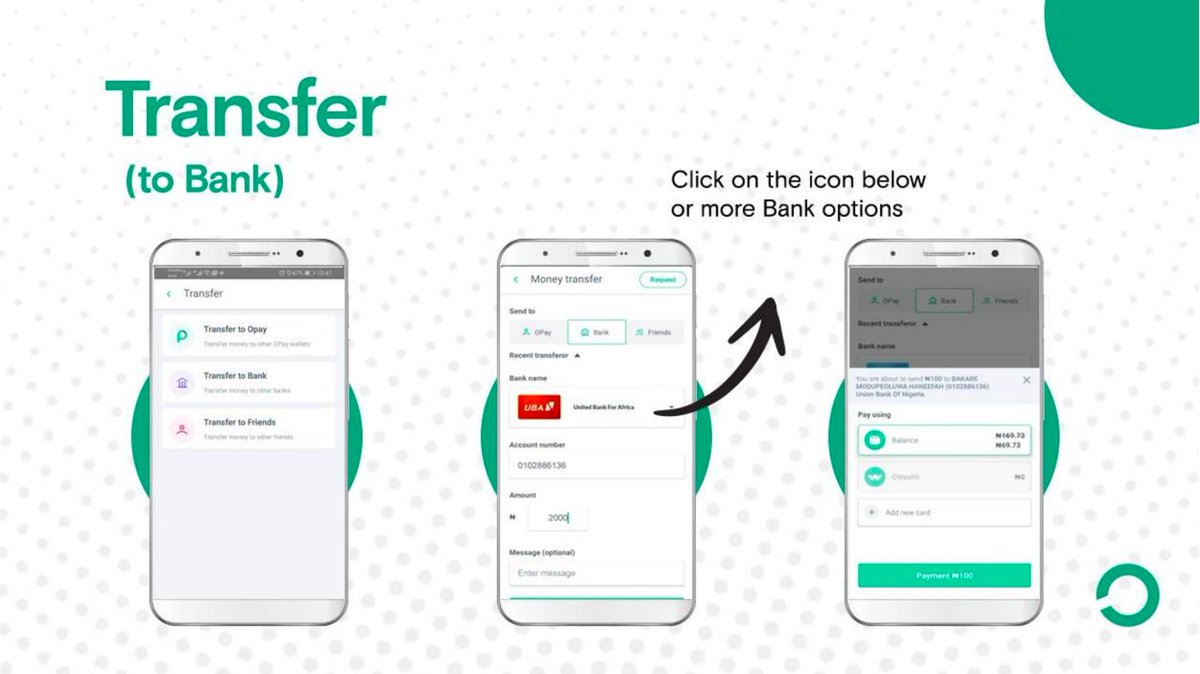
- Massive data privacy breach
1) internet browser history
2) social media
3) SMS and call history
4) location data
- high loan origination fee (upwards of 22%)
- massive APR (upwards of 300%)
- short term fixed duration (not suitable for farmers)
You cannot afford a 22% loan origination fee and don't want to consent to such invasive privacy access, you seem to be out of options.
Enter @liqwidfinance.
@liqwidfinance will be the first money market borrow/lending on-chain application on #Cardano. This will enable anyone with $ADA or on-chain stable coin to engage as a lender/supplier in the market to earn interest or to borrow against their assets.
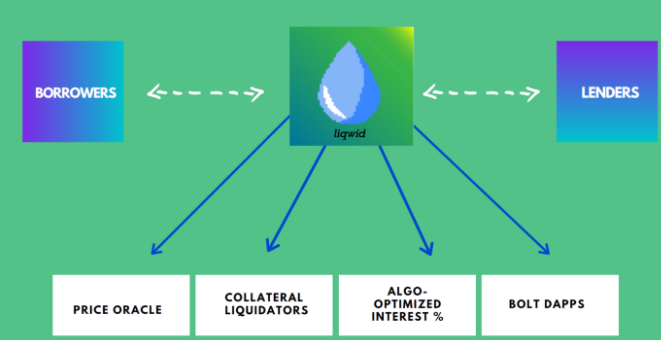
This is only a high-level view as I will post a separate thread digging into the details and technology behind @liqwidfinance.
The removal of custody, settlement, and escrow with their heavy fixed costs built into the legacy CeFi system
and the introduction to algorithmically optimized money, like @liqwidfinance lowers the fees charged to perform key banking actions.
What this looks like for Kamali is a loan origination fee ~100x smaller than her current CeFi incumbent, Opay – currently 22% – at .25%.
@liqwidfinance will be working on ‘credit concepts’ that will enable a completely decentralized, on-chain credit scoring system which will allow for dynamic, algorithmically set interest rates that will incentivize borrowers like Kamali to make her loan payments on time.
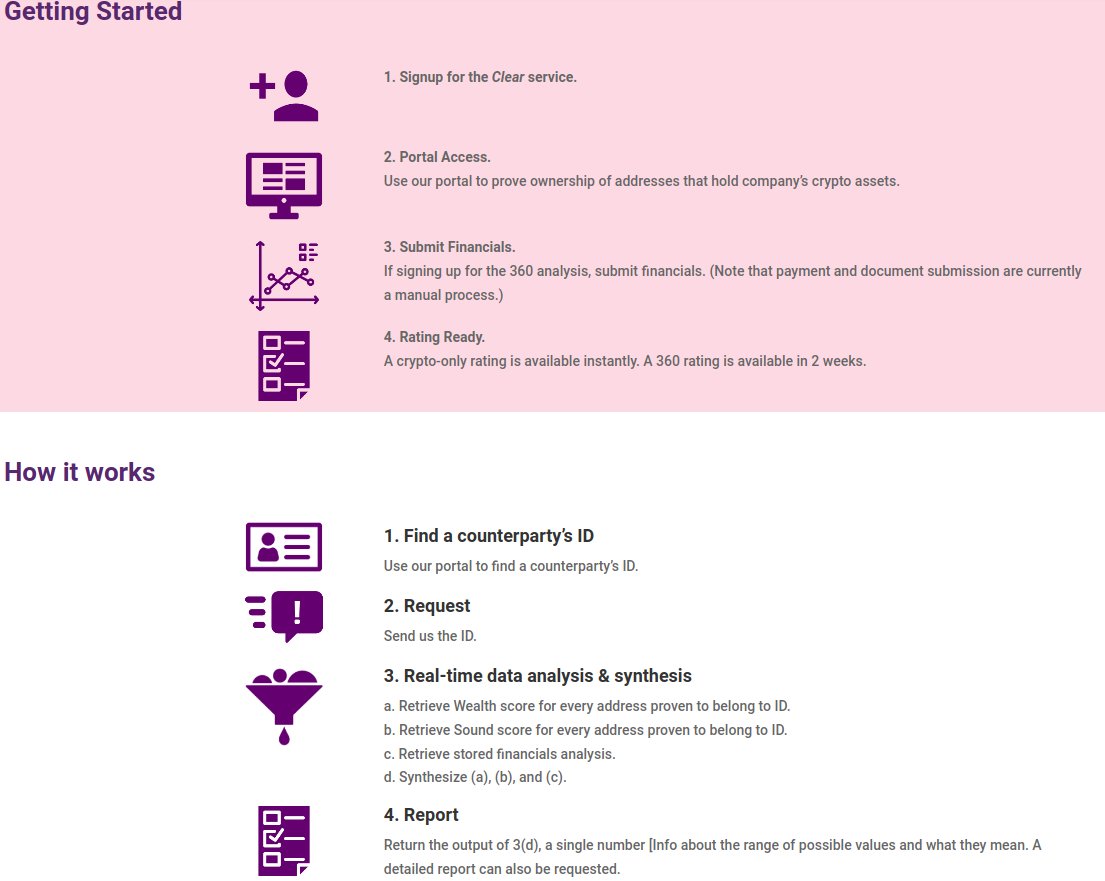
To do this, it would be important for @iohk to open-source Atala PRISM to applications like @liqwidfinance as it is the most robust identity solution framework.
Lets jump back in with Kamali:
You have now secured financing and can borrow against your new found liquidity to obtain the credit voucher you were previously denied by the financial institution; the credit voucher allows you to pay a subsidized rate for inputs, usually 60%.
Your demand for expansion has now been met and you begin harvesting wheat and other crops on all 1.75 hectares, and guess what? Your entire village and other villages around you start taking the same approach.
Now the aggro-dealers are struggling keeping up with the new demand as their source of funding (financial institution + regional government) doesn't have the capital to pay importers, suppliers and input producers.
With FDI already at all time highs, how and where do we introduce more liquidity to keep up with growing input demand?
While the financial bottle necking in Ethiopia forces illiquidity and further expands financial exclusion from capital on-ramps across the globe,
the bridge to this is being built in DeFi and with the introduction of tokenization could provide liquidity to the near 5 trillion dollars in illiquidity that exists in Africa.
Currently, the financial institutions that distribute credit vouchers are backed by regional governments through the Commercial Bank of Ethiopia but most credit and cash sales are collected and facilitated by the financial institutions
themselves therefore mitigating budget risks for regional governments. These individual vouchers are 100% sovereign-backed and have a 90% repayment rate with a 15% interest.
While these vouchers are small individually, what if it was possible to tokenize them,
aggregate them, then create tranches based off of crop, harvest-rate and seasonal production which have maturation dates built in to provide investors varied risk profiling. You could call these debt instruments tABS’s or (tokenized asset-backed securities)
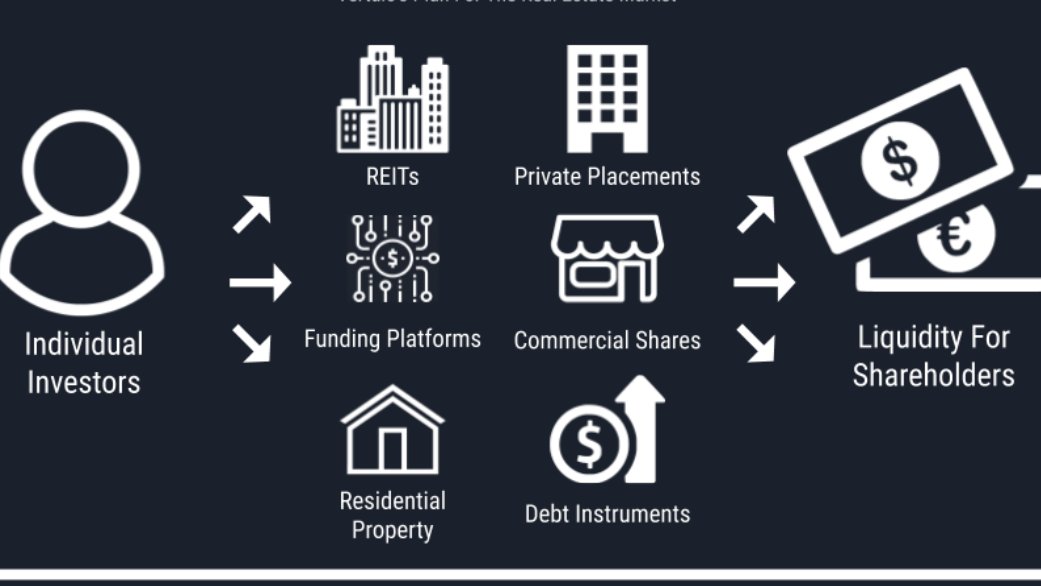
and they would live on the #Cardano blockchain and could be sold to hedge funds, investment banks, or individual investors in the #Cardano ecosystem.
Lets jump back into Africa:
Capital inflows into the financial institutions are pouring in and they can now fund the growing demand for agricultural inputs from suppliers. Agro-dealers and cooperatives have sufficient supply for small-hold farmers and production beings to see exponential growth.
Kamali has leveraged an emerging product that allowed her to set a new precedence for her community members. They begin to copy her business model, and word gets out and now her strategy has cascaded internationally throughout all of Sub-Saharan Africa.
There are many more problems that exist within this example, for instance post-harvest strategy, lack of storage-infrastructure, predatory agricultural brokers, road/railway infrastructure, and current import/export protocols
that could easily be solved by #Cardano and products like Atala TRACE, but for the sake of brevity, we will stop here.
More from Trading







You May Also Like



1/ Some initial thoughts on personal moats:
Like company moats, your personal moat should be a competitive advantage that is not only durable—it should also compound over time.
Characteristics of a personal moat below:
2/ Like a company moat, you want to build career capital while you sleep.
As Andrew Chen noted:
3/ You don’t want to build a competitive advantage that is fleeting or that will get commoditized
Things that might get commoditized over time (some longer than
4/ Before the arrival of recorded music, what used to be scarce was the actual music itself — required an in-person artist.
After recorded music, the music itself became abundant and what became scarce was curation, distribution, and self space.
5/ Similarly, in careers, what used to be (more) scarce were things like ideas, money, and exclusive relationships.
In the internet economy, what has become scarce are things like specific knowledge, rare & valuable skills, and great reputations.
Like company moats, your personal moat should be a competitive advantage that is not only durable—it should also compound over time.
Characteristics of a personal moat below:
I'm increasingly interested in the idea of "personal moats" in the context of careers.
— Erik Torenberg (@eriktorenberg) November 22, 2018
Moats should be:
- Hard to learn and hard to do (but perhaps easier for you)
- Skills that are rare and valuable
- Legible
- Compounding over time
- Unique to your own talents & interests https://t.co/bB3k1YcH5b
2/ Like a company moat, you want to build career capital while you sleep.
As Andrew Chen noted:
People talk about \u201cpassive income\u201d a lot but not about \u201cpassive social capital\u201d or \u201cpassive networking\u201d or \u201cpassive knowledge gaining\u201d but that\u2019s what you can architect if you have a thing and it grows over time without intensive constant effort to sustain it
— Andrew Chen (@andrewchen) November 22, 2018
3/ You don’t want to build a competitive advantage that is fleeting or that will get commoditized
Things that might get commoditized over time (some longer than
Things that look like moats but likely aren\u2019t or may fade:
— Erik Torenberg (@eriktorenberg) November 22, 2018
- Proprietary networks
- Being something other than one of the best at any tournament style-game
- Many "awards"
- Twitter followers or general reach without "respect"
- Anything that depends on information asymmetry https://t.co/abjxesVIh9
4/ Before the arrival of recorded music, what used to be scarce was the actual music itself — required an in-person artist.
After recorded music, the music itself became abundant and what became scarce was curation, distribution, and self space.
5/ Similarly, in careers, what used to be (more) scarce were things like ideas, money, and exclusive relationships.
In the internet economy, what has become scarce are things like specific knowledge, rare & valuable skills, and great reputations.