1/ About the company
Developer & manufacturer of high value, non- commoditized APIs (complex & low competition) in chronic therapeutic areas: CVS, CNS, pain management & diabetes, etc
Basic details about the IPO 👇
Note: After paying off liabilities, 150crs remain for capex.
2/ The Journey
Established the API business in FY02
Since 2015, Have not received any adverse reactions from regulators (USFDA, PMDA) in the total 38 audits & inspections & Have gone through 432 customer audits.
Filled 403 DMFs & CEP registration across markets globally.
3/ Trends that the company is betting on & what works for them
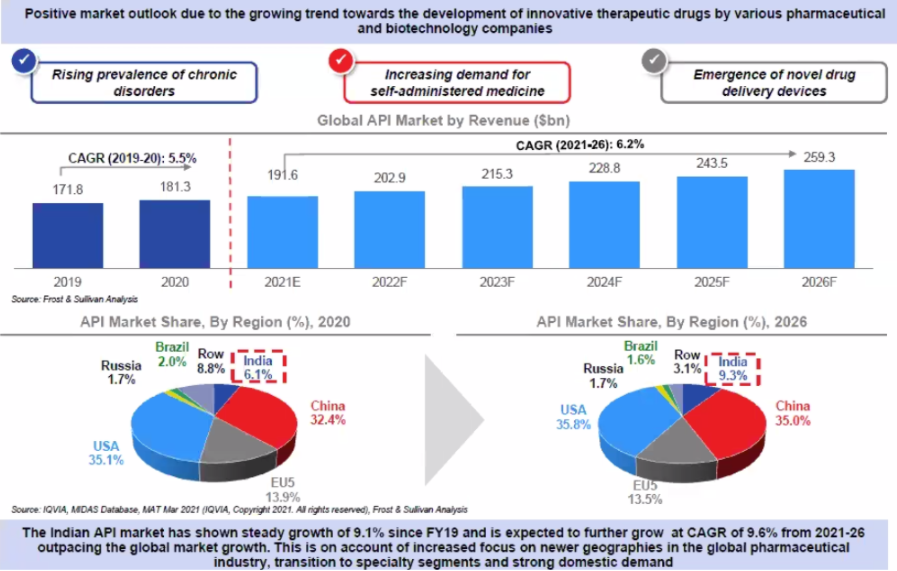
China+1: India API market growth (10% cagr projected from FY21-26) will outpace the industry: Driven by specialty API+ Strong domestic market
Highest no. of USFDA approved API facilities & % of DMFs filled
4/ Interesting facts
- 120 molecules: $142B market size
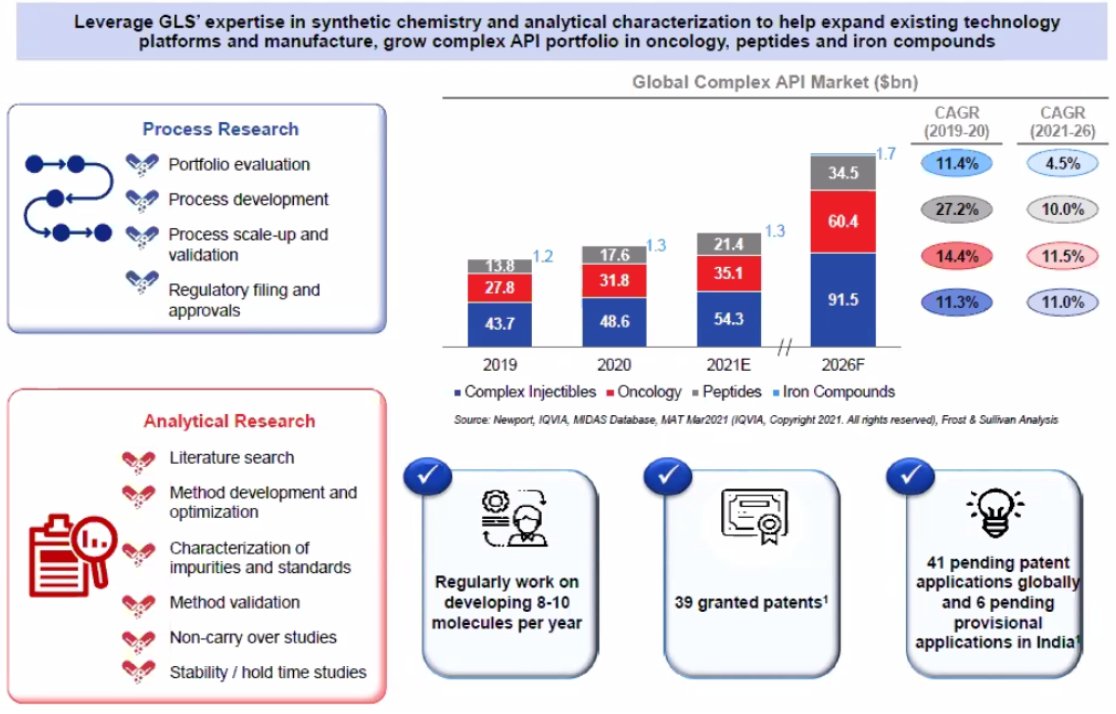
- Targetting 8 to 10 new molecules every yr (Key differentiator over time)
- 66% of sales from regulated markets
- Works with 16 of the top 20 generic cos.
- Top 7 customers: 5 to 15yrs old
5/ API Portfolio
Key products in generic API business 👇 (Shows cost leadership in few molecules as market share is 30%+)
Strategy to mix: High value & High Volume APIs
Complex API is a future growth market: Going into the development of Peptide APIs by FY22.
6/ R&D: the secret ingredient
Spends 2-2.5% of rev every year
39 patents under the belt
213 R&D personnel in 3 dedicated facilities
Focus on cost improvements in existing products & developing newer products: onco, peptides, iron compounds
7/ Manufacturing Capacity & Capex
4 plants 762KL capacity, running at 85% capacity: 3 USFDA approved, 1 for emerging markets
Increasing capacity by 200KL in Dahej & Ankleshwar by FY23
Investing in a new greenfield capacity: will take it to aggregate 800KL capacity in 3-4yr
8/ Experienced Management with a proven track record: A total of 1537 permanent employees.
9/ CDMO business: 8-10% of their rev (will ramp up)
End of lifecycle management- when the innovator loses its patent & looks for a cheaper source of their API; they can choose GLS
The 🌎 trends that benefit this business 👇
10/ Financials
Rev scaled at 16% cagr from FY19-21
Margins consistently above 30% (high operational efficiency as GMs are 50-55%)
Stable cash flows: WC requirements are high, OCF & debt would be enough to increase capacity over the next 4-5yrs
11/ Risks:
- High Customer churn: Only 41% of the customers stayed from FY19 to FY21.
- Imports 40% of RM from China: could face huge pricing pressure which they are not able to pass on.
- Regulatory & compliance risks
- Client concentration: 56% of rev from the top 5 customers
12/
- Dependence on key products: Top 10 account for 66% of sales
- Capex implementation risk
- Multiple outstanding litigations against the promoter & the company
- COVID risk: some disruptions in acute products & favipiravir sales benefit: net 2-3% +ve effect in FY21.
13/
- Increased competition in their respective products: pricing pressure
- Working capital risk: have huge credit terms up to 180 days
- High employee attrition of 18-20%
- Failure to get the environmental clearances for new facilities.
14/
We believe Glenmark Life sciences IPO which is currently valued at 4.6x EV/sales, 15x EV/EBITDA & 25x Price/Earnings & following the lucrative strategy to become bigger in complex APIs, is rather reasonably valued.
End of thread.
Comparison with the peers
- Top quartile EBITDA margins
- Low capex requirements & high asset turnover business
- Cash conversion cycle is one of the worst: Needs to invest a lot of working capital to grow if it doesn't improve
- Valuation wise, A discount to industry averages
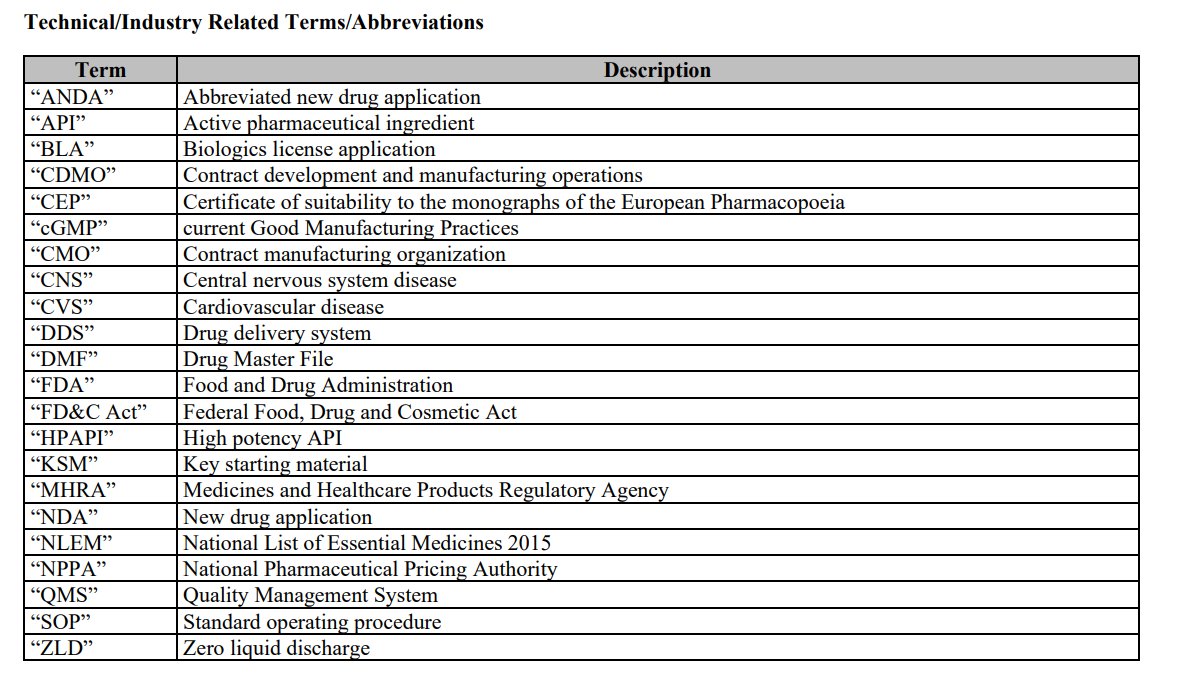
A glossary for the complex industry-related abbreviations I used above 👇