Window dressing: : the act or an instance of making something appear deceptively attractive or favorable
The day before the official visit trucks were pulling in with all kind of food stuff regular people didn't see in ages.
I predict you have a question: what would happen with the window dressing items after the visit ended?
Of course not.
Fact is, nobody knows what happened with it. Trucks would pull in the back of the store, the workers would load them.
"Tonight again on the news (3 X),
Tonight again on the news, I've seen cheese,
Chorus: tonight again on the news (3 X),
Tonight again on the news, I've seen cheese.
https://t.co/fEPvy5fjSK
I even watched until the end, but that's no problem - because:
Tomorrow again on the news (3 X)
Tomorrow again on the news, I shall see cheese again!
More from Economy

On Jan 6, 2021, the always stellar Mr @deepakshenoy tweeted, this:
https://t.co/fa3GX9VnW0
Innocuous 1 sentence, but its a full economic theory at play.
Let me break it down for you. (1/n)
On September 30, 2020, I wrote an article for @CFASocietyIndia where I explained that RBI is all set to lose its ability to set interest rates if it continues to fiddle with the exchange rate (2/n)
What do I mean, "fiddle with the exchange rate"?
In essence, if RBI opts and continues to manage exchange rate, then that is "fiddling with the exchange rate"
RBI has done that in the past and has restarted it in 2020 - very explicitly. (3/n)
First in March 2020, it opened a Dollar/INR swap of $2B with far leg to be unwound in September 2020.
Implying INR will be bought from the open markets in order to prevent INR from falling vis a vis USD (4/n)
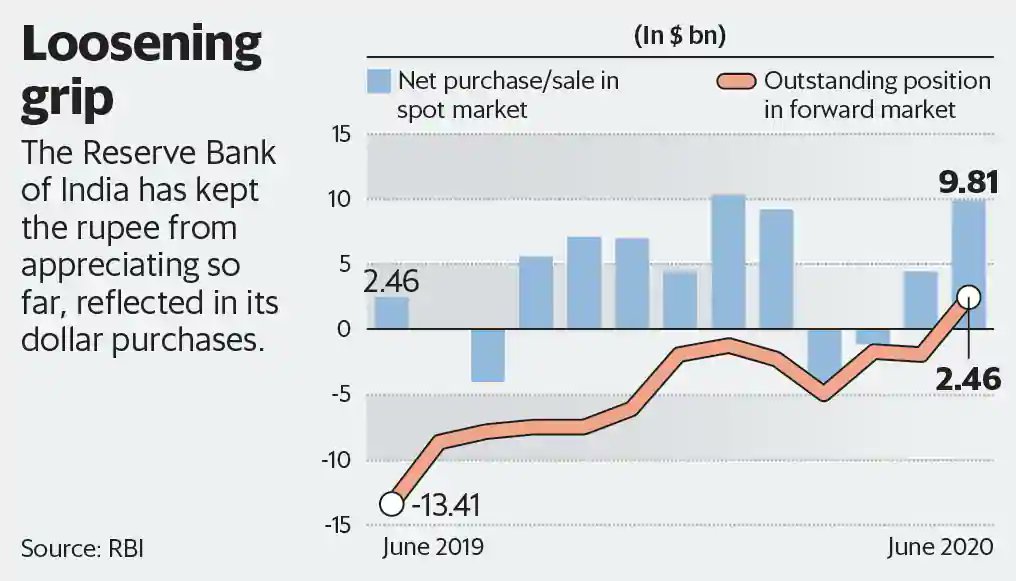
The Second aspect is now, that dollar inflow is happening, and the forex reserves swelled -> implying the rupee is appreciating, RBI again intervened from September, by selling INR in spot markets. (5/n)
https://t.co/9kpWP7ovyM
https://t.co/fa3GX9VnW0
Innocuous 1 sentence, but its a full economic theory at play.
Let me break it down for you. (1/n)
91 day TBills at 3.03%. Interest rates are even lower than RBI has them.
— Deepak Shenoy (@deepakshenoy) January 6, 2021
On September 30, 2020, I wrote an article for @CFASocietyIndia where I explained that RBI is all set to lose its ability to set interest rates if it continues to fiddle with the exchange rate (2/n)
What do I mean, "fiddle with the exchange rate"?
In essence, if RBI opts and continues to manage exchange rate, then that is "fiddling with the exchange rate"
RBI has done that in the past and has restarted it in 2020 - very explicitly. (3/n)
First in March 2020, it opened a Dollar/INR swap of $2B with far leg to be unwound in September 2020.
Implying INR will be bought from the open markets in order to prevent INR from falling vis a vis USD (4/n)
The Second aspect is now, that dollar inflow is happening, and the forex reserves swelled -> implying the rupee is appreciating, RBI again intervened from September, by selling INR in spot markets. (5/n)
https://t.co/9kpWP7ovyM



The argument for deficits & debt raising interest rates in the US is not increased credit risk, it is that interest rates are a function of economic fundamentals, flows & policy. Deficits/debt change those.
I can't tell if I'm agreeing or disagreeing with @jc_econ.
Increasing government spending or reducing taxes increases demand (or reduces saving). This raises the price of loanable funds or the interest rate.
In a dynamic context, more demand means a stronger economy, the central bank raises interest rates sooner, and long rates rise.
(As an aside, we are not close to the United States needing to worry about credit risk and the risks are more overstated than understated in most other advanced economies too. But credit risk is not always & everywhere irrelevant, just look at the UK in 1976 or Canada in 1994.)
Interest rates have fallen over the last 20 yrs while debt has risen. This does not necessarily mean that debt rising causes interest rates to fall. It could also mean that other things have happened at he same time that pushed down interest rates more than debt pushed them up.
The suspects for these "other things" include slower productivity growth, slower popln growth, higher inequality, less investment, etc. All of which either increase the supply of saving or reduce the demand for investment, reducing the equilibrium interest rate.
I can't tell if I'm agreeing or disagreeing with @jc_econ.
There is no relationship b/w deficits & interest rates in the US & many other advanced economies. Centuries of dynamic institution building underpin our reserve currency status that allows rates to be a function of economic fundamentals, flows & policy not credit risk 1/3
— Dr. Julia Coronado (@jc_econ) January 26, 2021
Increasing government spending or reducing taxes increases demand (or reduces saving). This raises the price of loanable funds or the interest rate.
In a dynamic context, more demand means a stronger economy, the central bank raises interest rates sooner, and long rates rise.
(As an aside, we are not close to the United States needing to worry about credit risk and the risks are more overstated than understated in most other advanced economies too. But credit risk is not always & everywhere irrelevant, just look at the UK in 1976 or Canada in 1994.)
Interest rates have fallen over the last 20 yrs while debt has risen. This does not necessarily mean that debt rising causes interest rates to fall. It could also mean that other things have happened at he same time that pushed down interest rates more than debt pushed them up.
The suspects for these "other things" include slower productivity growth, slower popln growth, higher inequality, less investment, etc. All of which either increase the supply of saving or reduce the demand for investment, reducing the equilibrium interest rate.