https://t.co/XqDtKBcrAD
0/ A holiday economic theory reading list. Some of my favorite pieces on theory that can be read with minimal sweat, but with the maximal intellectual reward. In no particular order:
https://t.co/XqDtKBcrAD
https://t.co/RnCg0JIl07.
https://t.co/xO2BnIYlhw?
https://t.co/bYPAsWbJ8G
https://t.co/3jDTnzdt3c
https://t.co/OtwEP9pyks
Robinson's 1932 publication is 20pages \u201cEconomics is a Serious Subject: the apologia of an economist to the mathematician, the scientist and the plain man,\u201d and I can\u2019t find a full version. If you have it, I\u2019d love to read a copy for the genealogy of a concept I\u2019m working on, thx
— Beatrice Cherrier (@Undercoverhist) May 27, 2019
https://t.co/uVTHNnTAMc
https://t.co/PRpTdpURDM
More from Economy




1/ Trend Factor: Any Economic Gains from Using Information over Investment Horizons? (Han, Zhou, Zhu)
"A trend factor using multiple time lengths outperforms ST reversal, momentum, and LT reversal, which are based on the three price trends separately."
https://t.co/udkvsdw2Lz
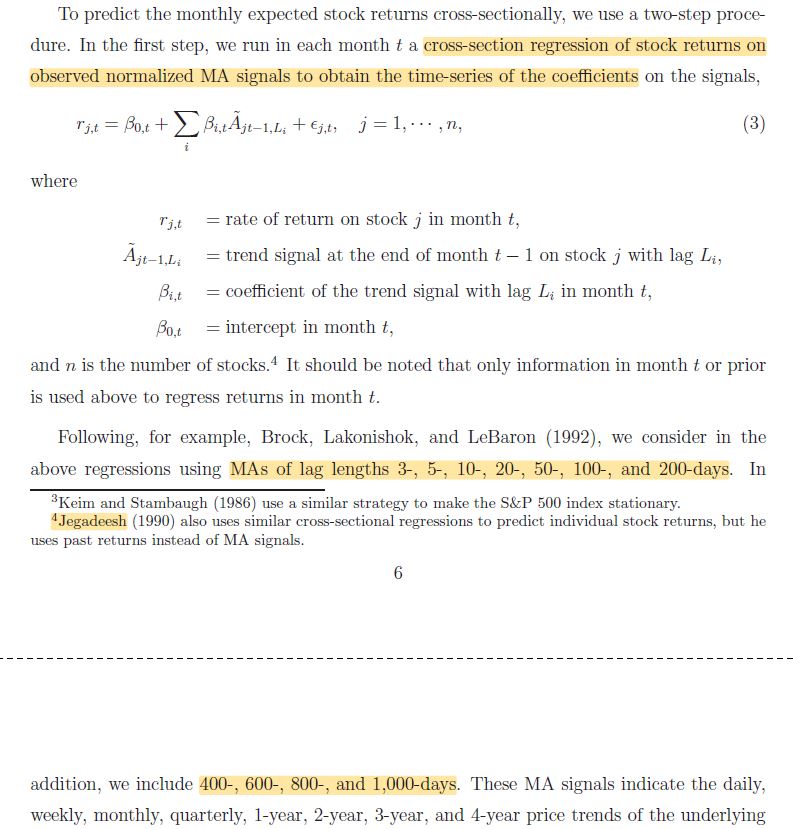
2/ This resembles combining multiple measures of ST reversal, momentum, and LT reversal (forecasts determined by walking forward rather than using signs from the full sample).
Unlike normal moving average signals, these are *cross-sectional.* More below:
https://t.co/wkIFLg9jtK
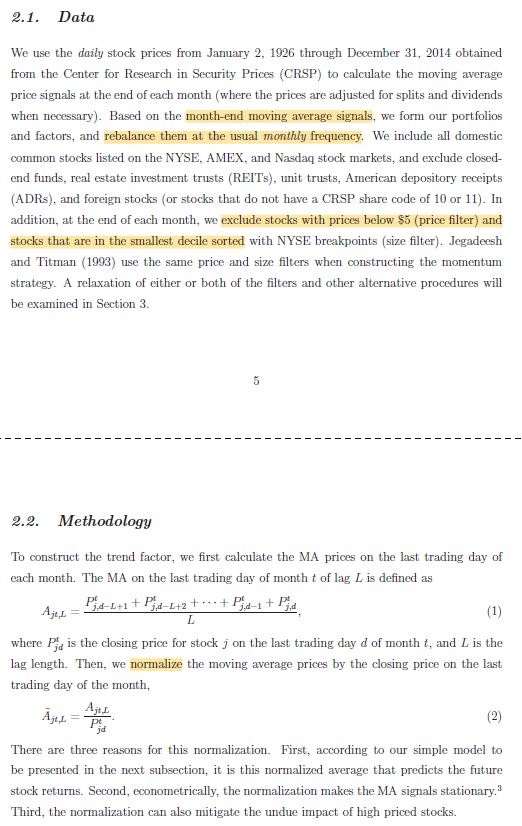
3/ Unsurprisingly, the Trend factor formed by this approach outperforms benchmarks in terms of both Sharpe ratio and tail metrics. It's combining momentum with two factors that are negatively correlated to it AND using multiple specifications.
More here:
https://t.co/x8Tloz3iyL
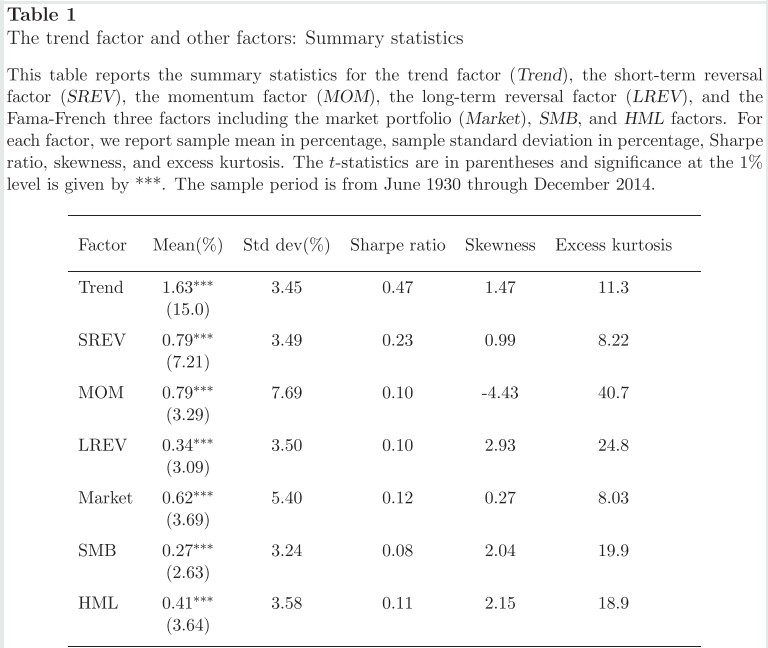
4/ "Average return and volatility of the trend factor are both higher in recession periods. However, the Sharpe ratio is virtually the same.
"Interestingly, all of the factors still have positive average returns.
"Momentum experiences the greatest increase in volatility."
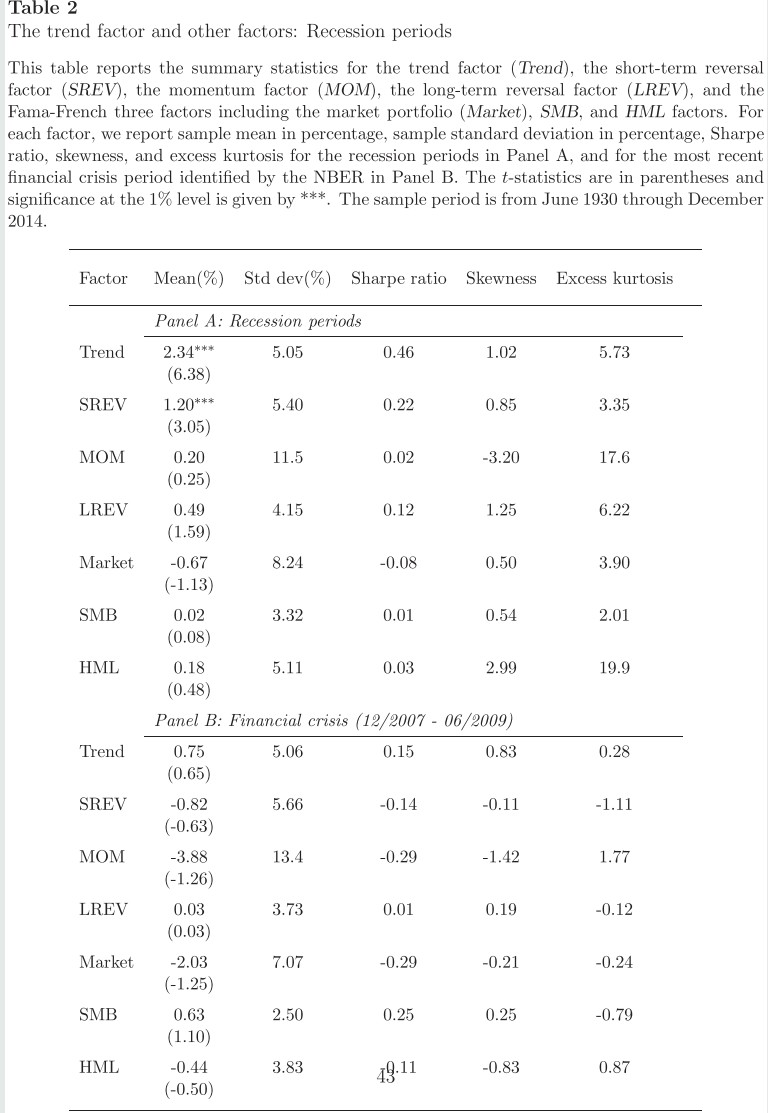
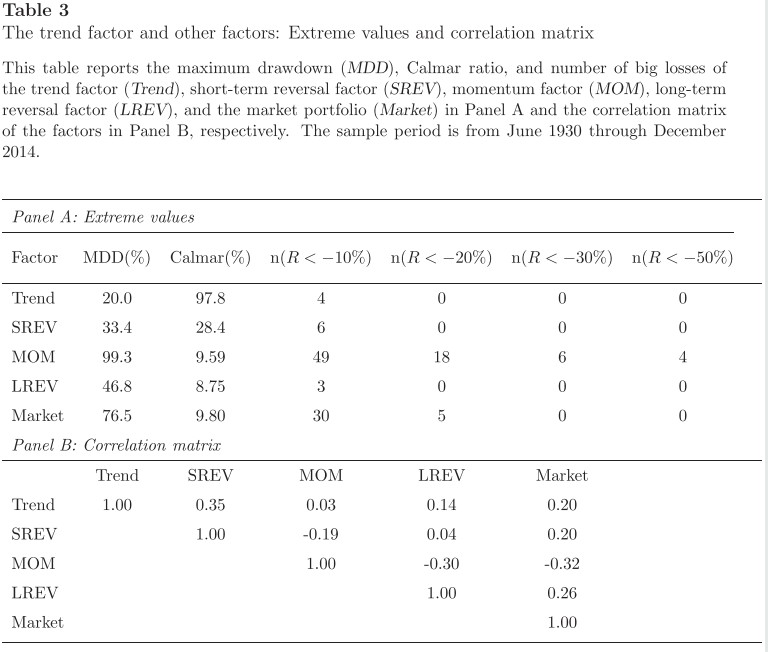
5/ "In terms of maximum drawdown and the Calmar ratio, the trend factor performs the best.
"The trend factor is correlated with the short-term reversal factor (35%), long-term reversal factor (14%), and the market (20%) but is virtually uncorrelated with the momentum factor."
"A trend factor using multiple time lengths outperforms ST reversal, momentum, and LT reversal, which are based on the three price trends separately."
https://t.co/udkvsdw2Lz
2/ This resembles combining multiple measures of ST reversal, momentum, and LT reversal (forecasts determined by walking forward rather than using signs from the full sample).
Unlike normal moving average signals, these are *cross-sectional.* More below:
https://t.co/wkIFLg9jtK
1/ Cross-Sectional and Time-Series Tests of Return Predictability: What Is the Difference? (Goyal, Jegadeesh)
— Darren \U0001f95a (@ReformedTrader) June 18, 2019
"The difference between the performances of TS and CS strategies is largely due to a time-varying net-long investment in risky assets."https://t.co/CSIn3ujN2R pic.twitter.com/XHnVmIart4
3/ Unsurprisingly, the Trend factor formed by this approach outperforms benchmarks in terms of both Sharpe ratio and tail metrics. It's combining momentum with two factors that are negatively correlated to it AND using multiple specifications.
More here:
https://t.co/x8Tloz3iyL
1/ An Executive Summary (in Tweet form) of our new paper
— Adam Butler (@GestaltU) March 27, 2019
Dual Momentum \u2013 A Craftsman\u2019s Perspective
Download here: https://t.co/Y9GlGNohBg
Everything that follows in this thread is based on HYPOTHETICAL AND SIMULATED RESULTS. pic.twitter.com/9m5YJnTdtq
4/ "Average return and volatility of the trend factor are both higher in recession periods. However, the Sharpe ratio is virtually the same.
"Interestingly, all of the factors still have positive average returns.
"Momentum experiences the greatest increase in volatility."
5/ "In terms of maximum drawdown and the Calmar ratio, the trend factor performs the best.
"The trend factor is correlated with the short-term reversal factor (35%), long-term reversal factor (14%), and the market (20%) but is virtually uncorrelated with the momentum factor."

You May Also Like




1/Politics thread time.
To me, the most important aspect of the 2018 midterms wasn't even about partisan control, but about democracy and voting rights. That's the real battle.
2/The good news: It's now an issue that everyone's talking about, and that everyone cares about.
3/More good news: Florida's proposition to give felons voting rights won. But it didn't just win - it won with substantial support from Republican voters.
That suggests there is still SOME grassroots support for democracy that transcends
4/Yet more good news: Michigan made it easier to vote. Again, by plebiscite, showing broad support for voting rights as an
5/OK, now the bad news.
We seem to have accepted electoral dysfunction in Florida as a permanent thing. The 2000 election has never really
To me, the most important aspect of the 2018 midterms wasn't even about partisan control, but about democracy and voting rights. That's the real battle.
2/The good news: It's now an issue that everyone's talking about, and that everyone cares about.
3/More good news: Florida's proposition to give felons voting rights won. But it didn't just win - it won with substantial support from Republican voters.
That suggests there is still SOME grassroots support for democracy that transcends
4/Yet more good news: Michigan made it easier to vote. Again, by plebiscite, showing broad support for voting rights as an
5/OK, now the bad news.
We seem to have accepted electoral dysfunction in Florida as a permanent thing. The 2000 election has never really
Bad ballot design led to a lot of undervotes for Bill Nelson in Broward Co., possibly even enough to cost him his Senate seat. They do appear to be real undervotes, though, instead of tabulation errors. He doesn't really seem to have a path to victory. https://t.co/utUhY2KTaR
— Nate Silver (@NateSilver538) November 16, 2018