🌁BUSINESS
🏷Part of prestigious TATA Group
🏷Established in 1989, A forward looking IT business
🏷Company earns revenue primarily from providing information technology, engineering design, systems integration & support services, sale of licenses and maintenance of equipment
🌁The company operates in 2 segments
1. Software Development & Services
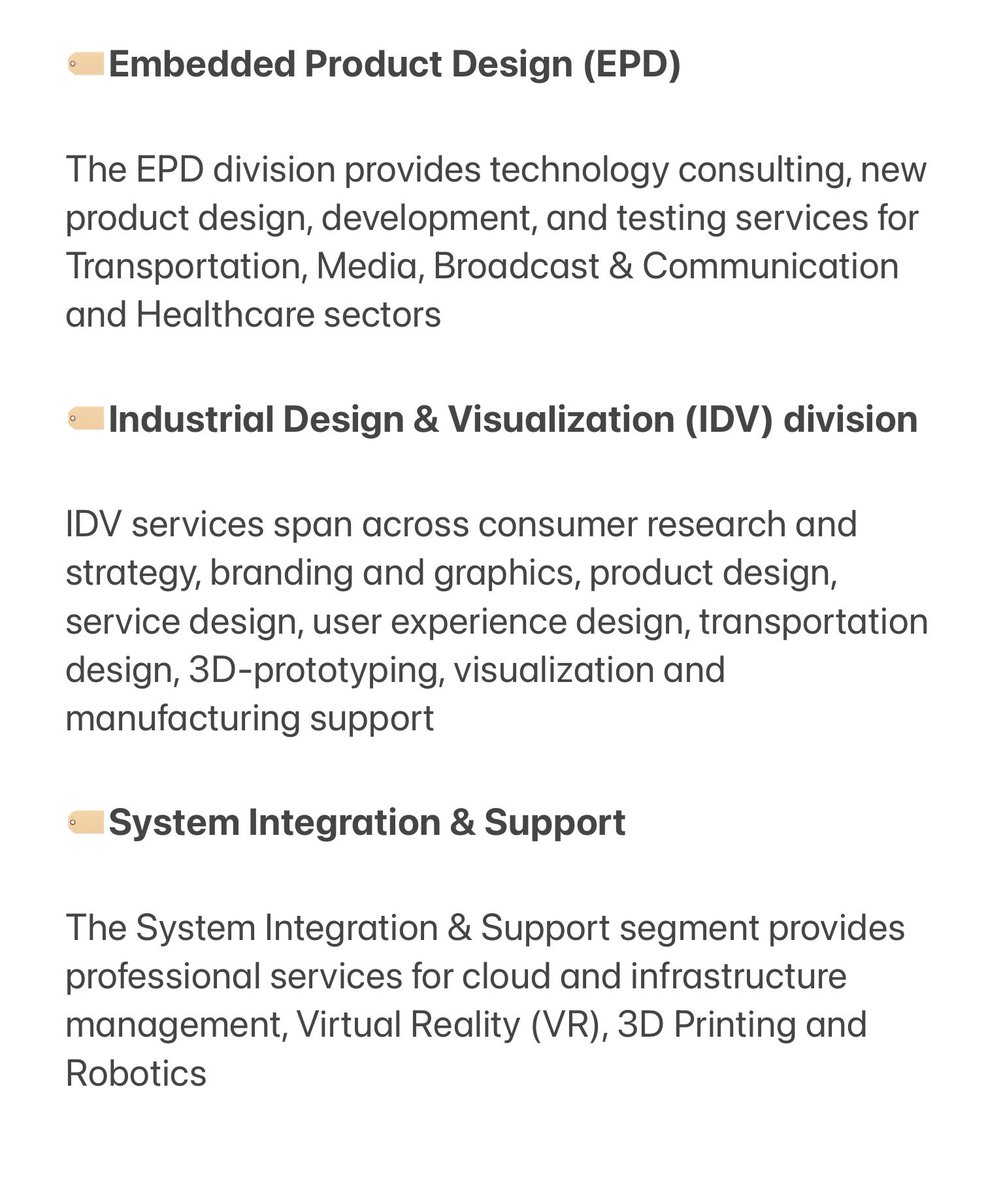
It is further sub divided into EPD and IDV.
🏷Embedded Product Design (EPD)
🏷Industrial Design & Visualisation (IDV) division
2. System Integration & Support (SIS)
🌁MANAGEMENT
🏷Manoj Raghavan (MD & CEO) : 22 Years of experience (2.42 Yrs tenure)
🏷CEO compensation ($USD 578.96K) is below average for companies of similar size
🏷CEO compensation has increased by more than 20% in the past year
🌁SHAREHOLDING PATTERN
🏷Change in promoter holding (Vs last quarter): -0.21%
🏷Change in FII holding (Vs last quarter): -0.78%
🏷Change in DII holding (Vs last quarter): +0.59%
🏷Change in public holding (Vs last quarter): +0.41%
🌁CONTRIBUTION TO DIFFERENT INDUSTRIES
Company is mainly working for below industries
1. Automotive
2. Broadcast & Communications
3. Healthcare
🌁WELL DIVERSIFIED REVENUE MIX (Q3 FY22)
🏷Geography
Americas: 42.3%, Europe: 32.8%, India: 16.7%, RoW: 8.2%
🏷Segment
Embedded Product Design: 88.9%
Industrial Design & Visualisation: 8.9%
System Integration & Support: 2.2%
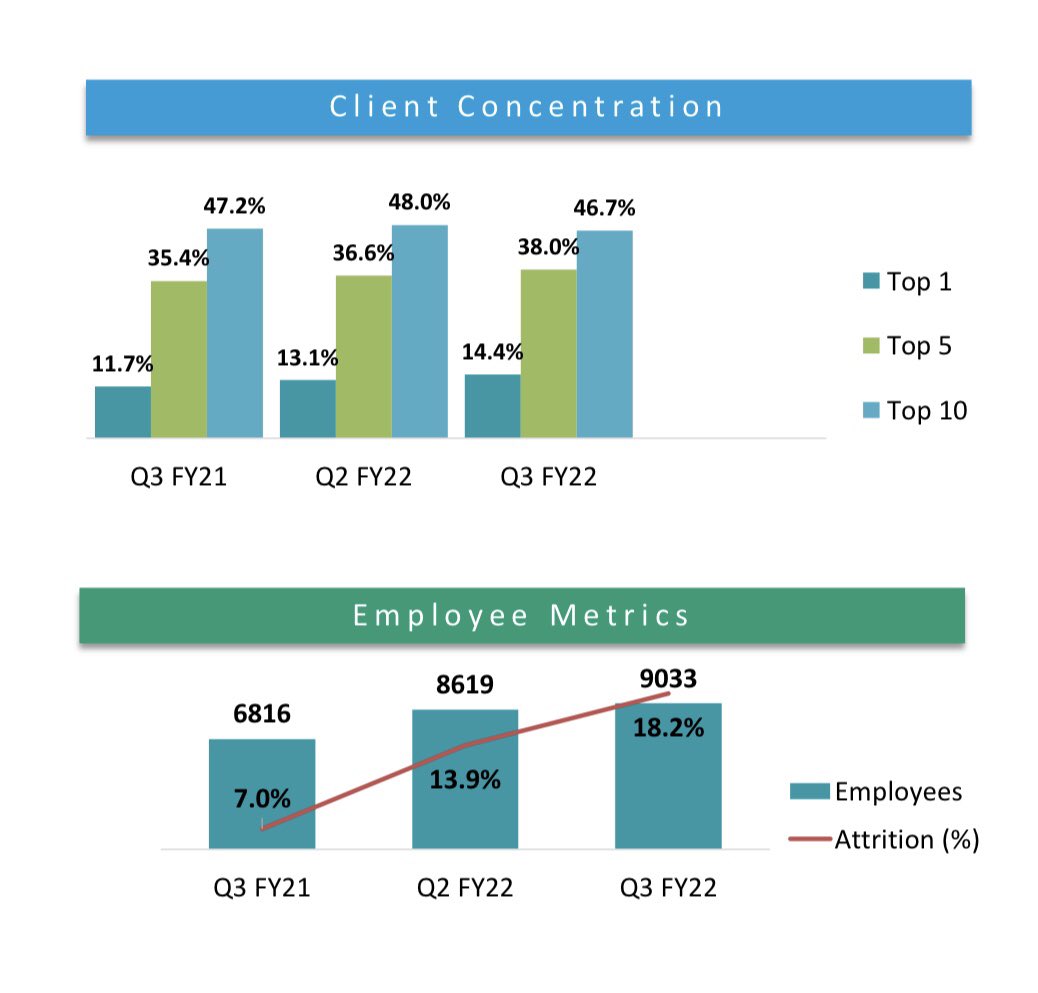
🌁Client concentration & Employee Metrics
🏷People addition in Q3 FY22: 414
🏷Employee utilisation rate ~83%
❌Attrition Rate: 18.2% (LTM)
🌁QUARTERLY RESULTS (Q3 FY22)
🏷Sales Growth: 33.2% YoY - Good YoY Sales Growth
🏷Profit: 43.5% YoY - Good YoY Profit Growth
🏷Consistent growth in margins
🏷Strong order book and a healthy deal pipeline
🏷The company is debt free since long
🌁FINANCIALS (5 Year CAGR)
🏷Sales Growth: 11.2%
🏷EBITDA Growth: 16.2%
🏷PAT Growth: 18.9%
🏷ROCE: 42.5% (FY21)
🏷ROE: 30.2%
Working capital days of the company in FY21 stood at ~65 days
Free cash flow per share increased to 62 Rs in FY 21
Overall, Numbers look good.
🌁STRENGTHS
🏷Diversified geographical presence
🏷Established market position
🏷Healthy financial operations
🏷Major contributor to the transformation to Electric Vehicle
🏷Company consistently making profits
🏷Debt free since long
🏷Brokers upgraded recommendation
🌁WEAKNESS
🏷Trading at Premium Valuation
🏷Promoter and FII reduced the holding in Q3 FY22
🏷Good competition from KPIT and LTTS
🏷~88% revenue from one segment, Embedded Product Design
🌁VALUATION
🏷Price to Earnings (PE): 104 (Above it’s median PE 27.6)
🏷Price to book value: 40.7
🏷PEG Ratio: 5.53
Although there is bright growth prospect, at current levels stock is trading at premium valuation (Overvalued).
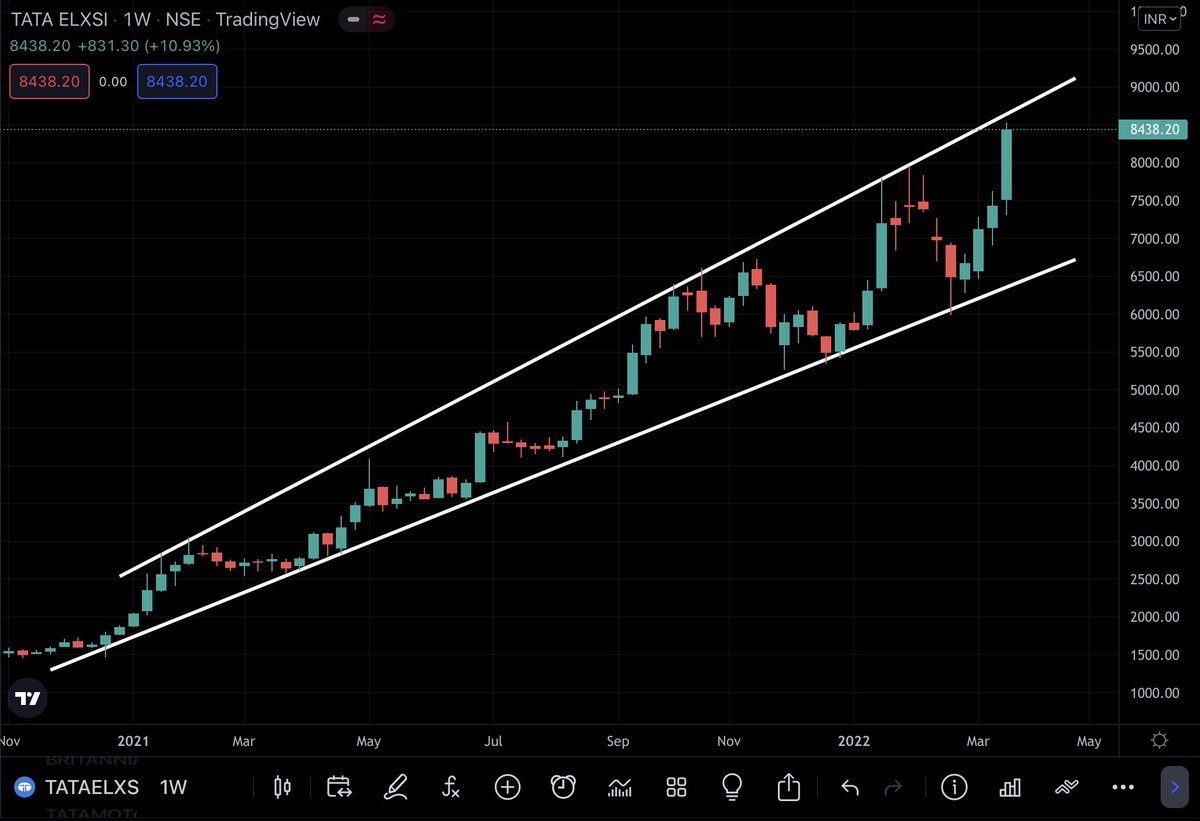
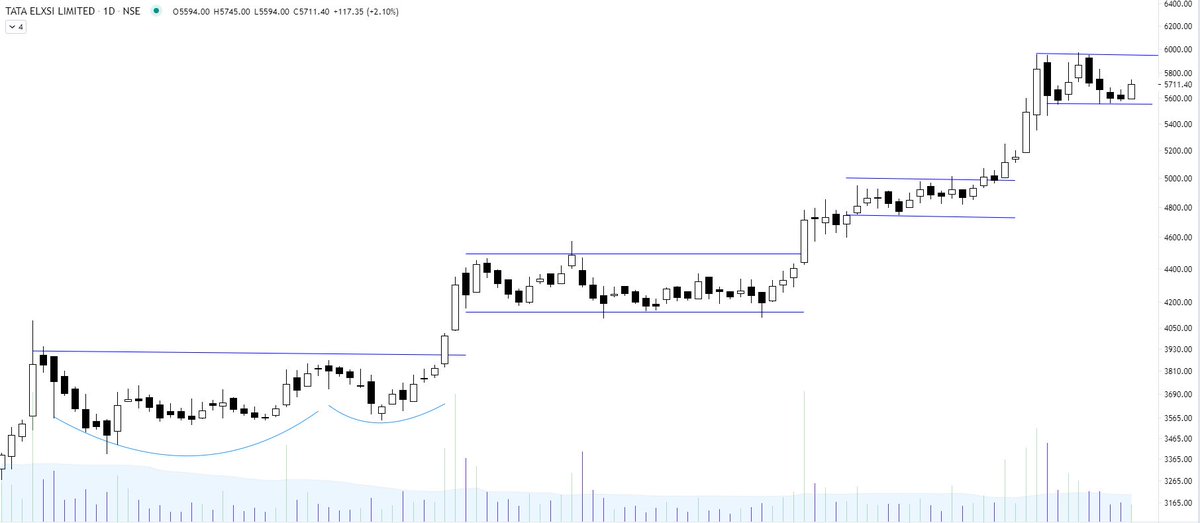
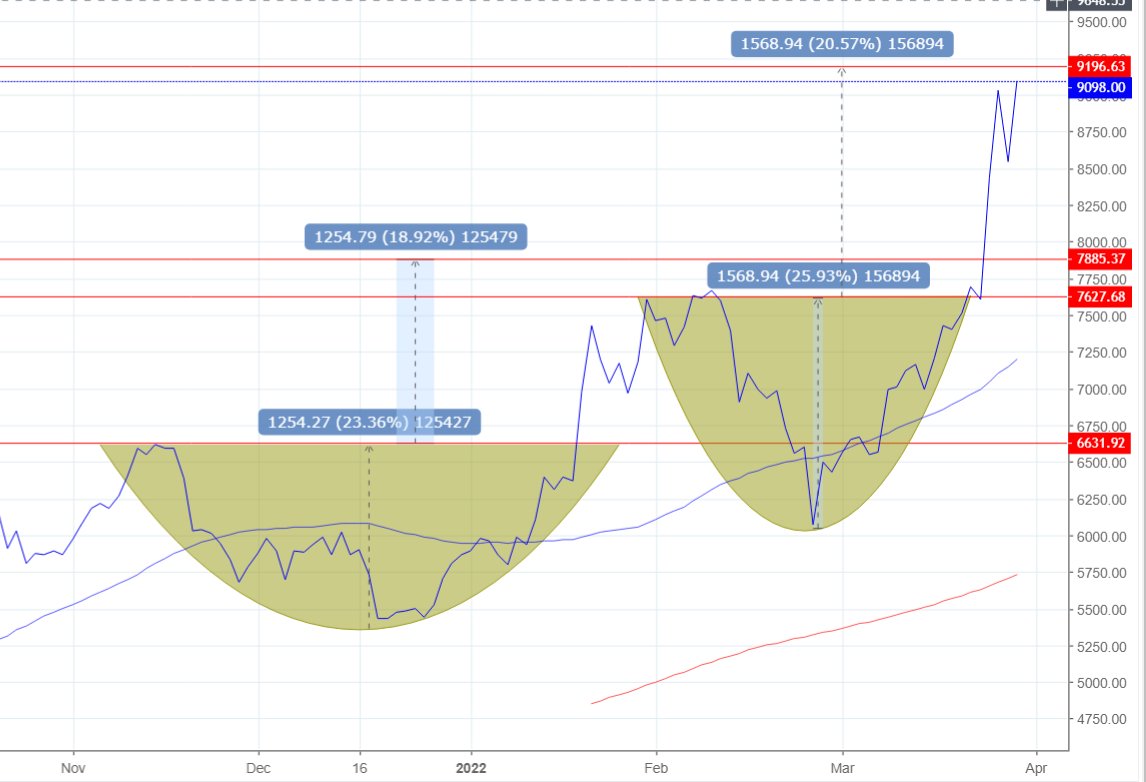
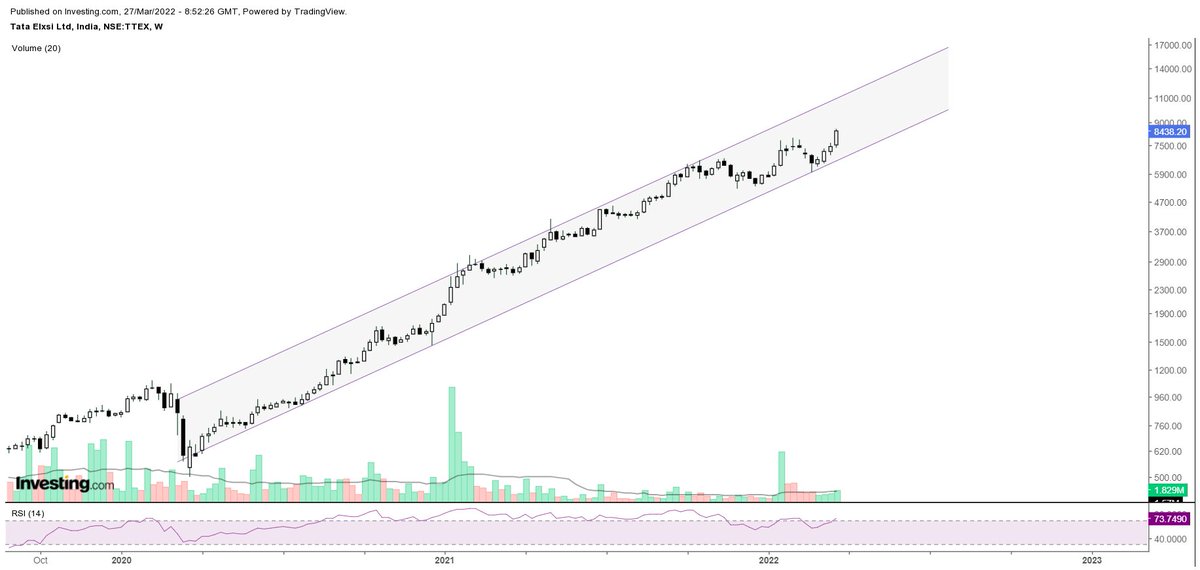
🌁CHART (Weekly Timeframe)