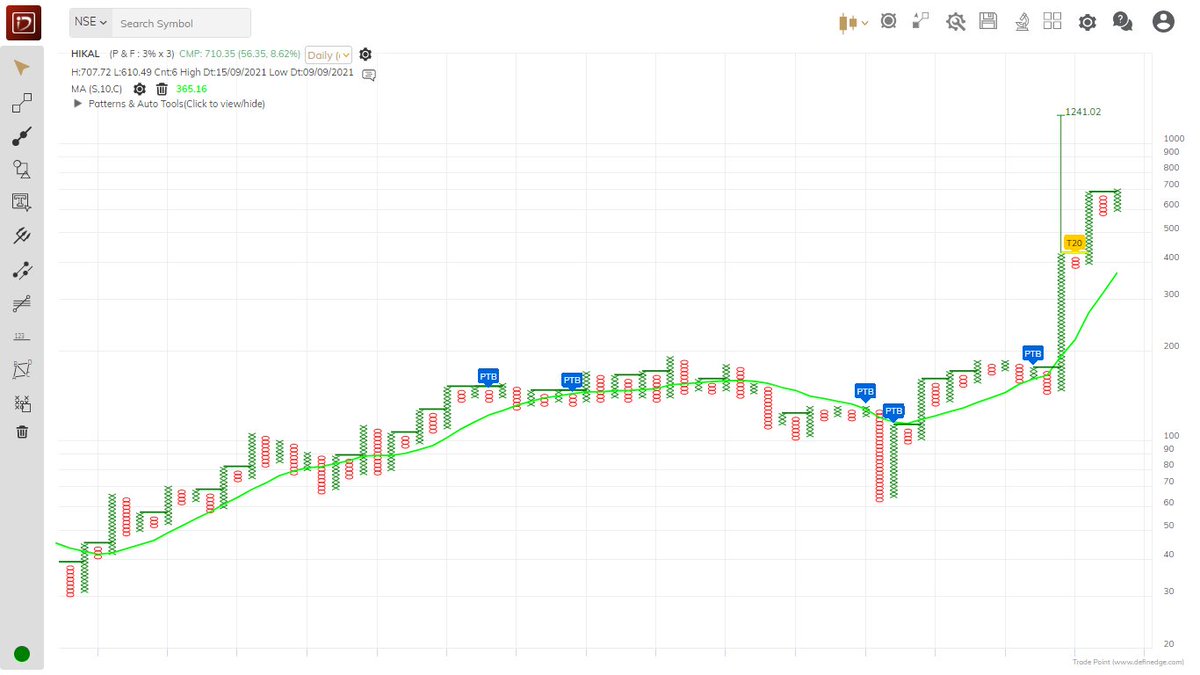
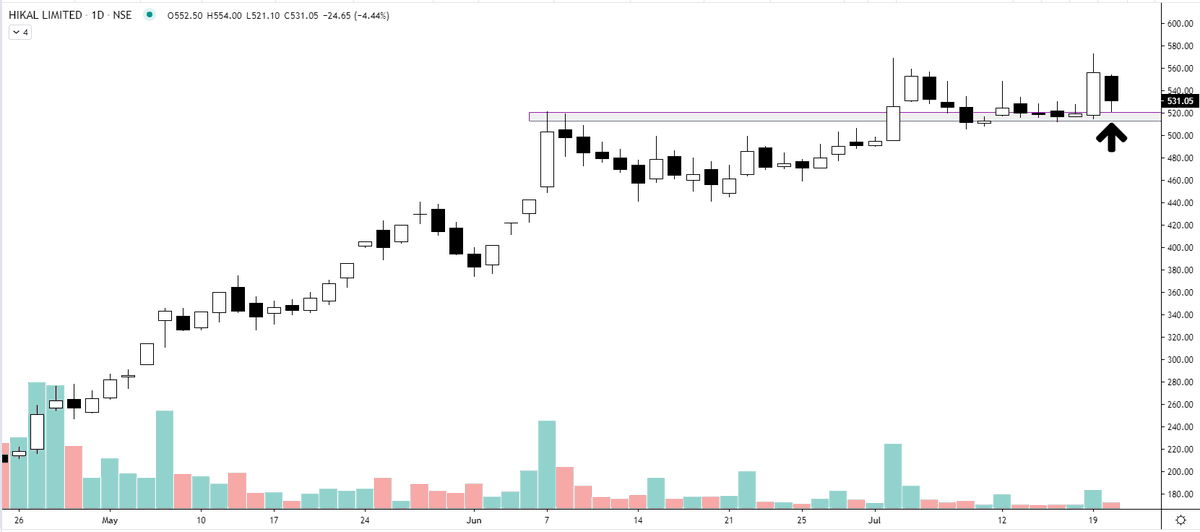
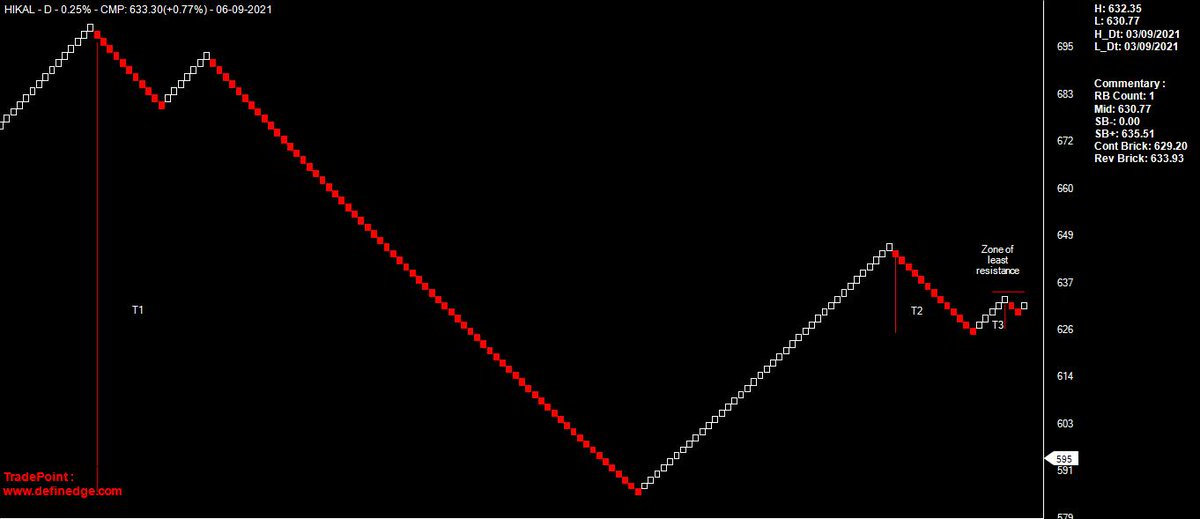
HIKAL Annual Report is a must read for everyone tracking the CDMO/API/Intermediates industry.
HIKAL being a hybrid player, their Annual Report insights on Pharma, Animal Health and Crop
More from Saket Reddy
Don't try bottom fishing and value buying as time correction can take away a lot of opportunity cost.
Just let it give a monthly or weekly close above ATH.
ABBOTINDIA
— Saket Reddy (@saketreddy) May 8, 2021
A breakout in the offing? pic.twitter.com/rnpcsQ616a
They are the real compounders, they've created massive wealth compared to others! https://t.co/PluVwU5OXG
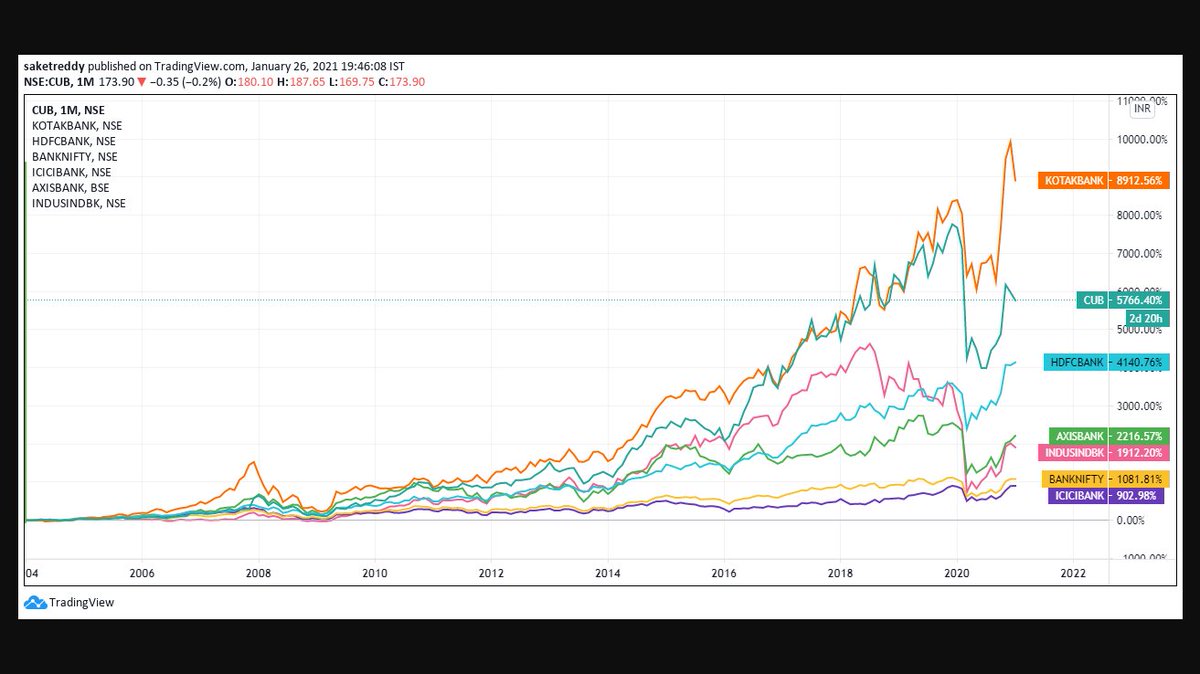
Hope Everyone saw BANDHANBNK Numbers. I feel many such banks will go through a massive NPA Cycle followed by depleted Tier 1.
— Saket Reddy (@saketreddy) January 24, 2021
Hence, stay with the Top 3 banks :-
HDFCBANK
KOTAKBANK
CUB
They've low cost of funding, well provisioned Moratorium book, high ROEs & high Tier 1 CAR.
The Home Building Theme has just broadened itself and is moving in top gear!
The best ways to play the real estate revival theme instead of buying the home builders :-
— Saket Reddy (@saketreddy) November 21, 2020
1. Ceramics (CERA, KAJARIA)
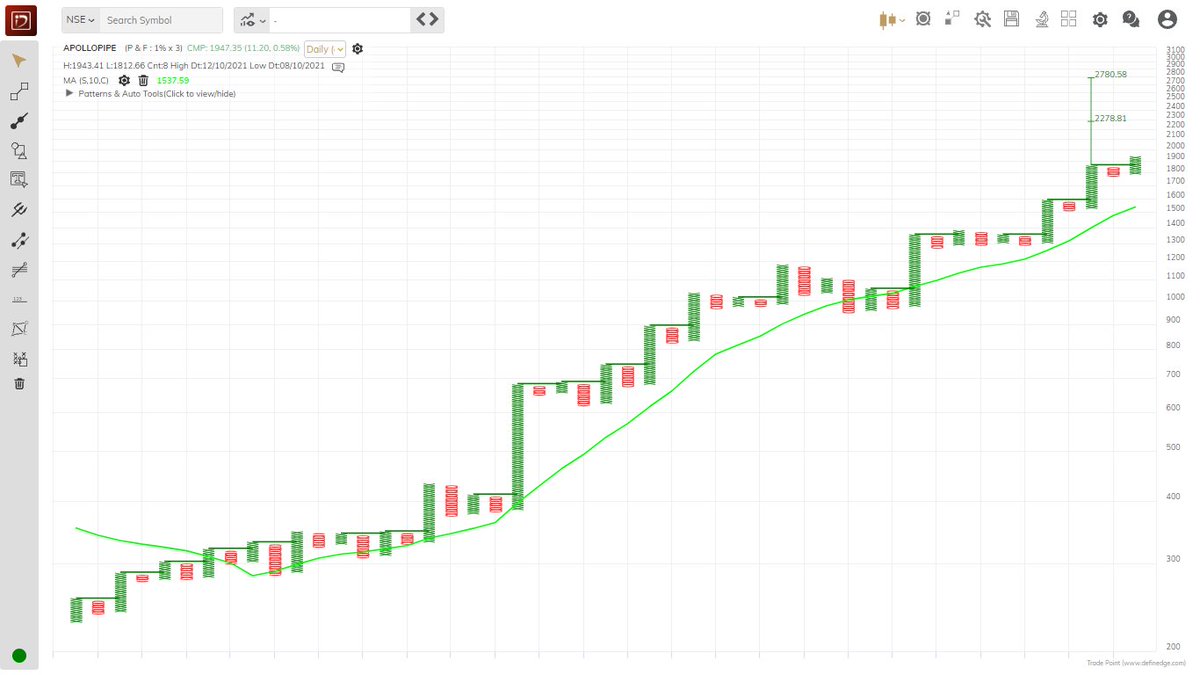
2. Pipes (ASTRAL, SUPREME, APLAPOLLO)
3. Paints (ASIAN, BERGER)
4. Cement (JKCEM, SHREEC)
5. Construction Chemicals (PIDILITE)
6. Electricals (POLYCAB, HAVELLS)
More from Hikal

🧪 Lowered interest rates
🧪 Pharma: Growth in generics as well as CDMO
🧪 Crop Protection: Scaleup of a fungicide for a Japanese CDMO client
🧪 Healthy pipeline of new products: Supported by new capacities; Investing in Animal Health & Biocides verticals https://t.co/D70j9oriCa

Hikal: Strong
— JST Investments (@JstInvestments) August 5, 2021
\U0001f9ea Rev up 27% YoY
\U0001f9ea 22% EBITDA margin
\U0001f9ea Pat of 50crs
\U0001f9ea Growth across both pharmaceuticals & crop protection.#Q1withJST #Pharma pic.twitter.com/8lFo68KzPe