HDFC Bank:Stable
🏦Profits grow at 18.2%
🏦Asset quality remains stable with credit costs at 1.65% for the quarter
🏦CAR at 18.8%
🏦Gross NPAs at 1.32% vs 1.38%
🏦HDB Financial returns to profits
🏦Watching carefully on how the second wave will turn out
(2/24)
ICICI Bank Results:-Stable
🏦Operating profit grows at 20%
🏦Covid-19 provisions increased by 1000cr to 7475cr
🏦Deposits grow by 21%
🏦Net NPA declines to 1.14%
🏦Capital Adequacy at 18.06%
🏦Retail loan growth at 20%
🏦Corporate loan growth at 13%
🏦Dividend-Rs 2/share
(3/24)
Cholamandalam Investment:Stable
🏦Disbursements decline 13%
🏦Loan loss provisions at 1.4%
🏦Profits up 29%
🏦Positive on Auto financing
(4/24)
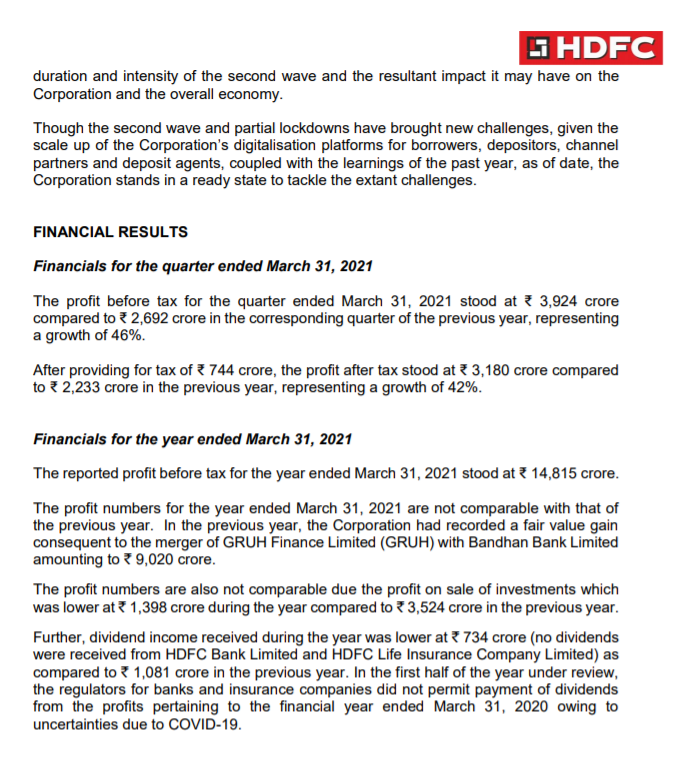
HDFC Ltd:Strong
🏦Loan disbursements grow 60%
🏦Month of March had highest ever disbursements
🏦Gross NPAs at 1.98%
🏦Individual loan NPAs at 0.99%
🏦Non-Individual Loan NPAs at 4.77%
🏦Dividend of Rs 23/share
🏦PAT grows by 19%
(5/24)
Bajaj Finance Results:Weak
🏦Interest income remains flat
🏦AUM rises marginally to 152,947cr
🏦Loan loss provision was 1231cr
🏦Writes off 1530cr
🏦PCR at 58%
🏦Gross NPAs at 1.79%
🏦Dividend of Rs 10/share
(6/24)
Axis Bank Results:Stable
🏦Loan growth at 12%
🏦Retail growth at 11%
🏦Corporate growth at 16%
🏦Slippages at 5285cr
🏦PCR at 72%
🏦Gross NPAs at 3.70%
🏦Restructured assets at 0.3%
(7/24)
AU Small Finance Results:Stable
🏦47% growth in disbursement
🏦Cost of funds reduces to 6.83%
🏦Gross NPAs at 4.3%
🏦Deposits grow by 38%
(8/24)
Can Fin Homes:Strong
🏦Disbursements increase by 44%
🏦Gross NPAs at 0.91%
🏦Loan book grows to 22,105cr
🏦Average Loan book size at 20 lakhs
(9/24)
Equitas Small Finance Bank:Weak
🏦Advances grow 17%
🏦Collection efficiency now below 90%
🏦Writes off 171cr of micro loans
🏦Provisions at 375 cr
🏦Gross NPAs at 3.56%
(10/24)
Indusind Bank:stable
🏦Assets grow by 18%
🏦Deposits grow by 27%
🏦Gross NPAs at 2.67%
🏦PCR at 75%
🏦Carries provisions of 8492cr
(11/24)
Kotak Mahindra Bank:Cautious
🏦Loan book grows at 1.8%
🏦Unsecured retail assets de-grow as a % of book
🏦Gross NPAs at 3.25%
🏦SMA-2 book at 0.05%
🏦435cr of loans restructured
🏦Holds 7021cr of COVID-19 provisions
(12/24)
RBL Bank:Weak
🏦Retail Advances grow by 13%
🏦Wholesale loans degrow by 12%
🏦Deposits grow by 26%
🏦Gross NPA at 4.34%
🏦PCR at 72.2%
🏦1439cr of loan written off
🏦1.41% of loans restructured.
(13/24)
Bandhan Bank:Weak
🏦Deposits grow 36.6%
🏦Loan portfolio grows at 21.2%
🏦GNPA at 6.8%
🏦Restructured loans worth 617cr
🏦Collection efficiency in Assam and Bengal remain affected
🏦Dividend of Rs 1/share
(14/24)
CSB Bank: Stable
🏛 Huge growth in gold loans as a % of total: 40% of book (high concentration)
🏛 Interest income up 27% | Asset quality weaker QoQ due to high slippages
🏛 Deposit growth at 21% | CAR at 21%
🏛 52% bank’s business comes from Kerala
(15/24)
L&T Finance Holdings:Stable
🏦All time high disbursals with 26% growth
🏦Microloans up 44%
🏦2 wheeler loans up 14%
🏦Farm Equipment loans up 40%
🏦Additional provision of 1003cr for COVID-19
🏦Stage 3 book at 1.57%
(16/24)
Aavas Financiers Results:Stable
🏦AUM grows by 21%
🏦Stage 3 assets increase to 0.98%
🏦No dividend declared
🏦81% Term Loans make up the borrowing profile
(17/24)
DCB Bank: Stable
🏦Loan grows 2% YoY
🏦Deposit degrows 2% (surprising)
🏦Gross NPA doubles to 4%, PCR at 62%
🏦CAR at 20%
(18/24)
DFC First Bank: Stable
🏛 Loans grew 7% QoQ & 10% YoY (26% YoY growth in retail & wholesale down 14%)
🏛 Deposits up 43% | CASA 52% | Reduced SA rates to 4-5% in May
🏛 4% GNPA | 56% PCR | 100%+ pre Covid collection efficiency in Q4
(19/24)
Federal Bank:Stable
🏦Advances grow by 9%
🏦Restructuring at 1409cr
🏦Collection efficiency at 95%
🏦Slippages at 1685cr
🏦Gross NPA at 3.41%
(20/24)
Canara Bank:Weak
🏦Advance grow at 1.14%
🏦Deposits grow at 3.89%
🏦Slippages at 4428cr
🏦SMA-0/1/2 at 22,938cr
🏦TIER-1 Capital Adequacy at 9.54%
(21/24)
Ujjivan Small Finance Bank:weak
🏦Advance up 7%
🏦Deposits up 20%
🏦Collection efficiency falls to 89% in April
🏦6.8% book restructured
🏦Gross NPA at 7.1%
🏦14.9% portfolio at risk
(22/24)
AB Capital:Weak
🏦Loan disbursement growth at 3%
🏦2.3% loan book restructured
🏦98.7% collection efficiency
🏦Housong Finance NPAs continue to riseHousing
🏦AMC reports the highest ever profit
(23/24)
Conclusion:-
🏦Large Banks continue to gain market share in deposits and loan growth
🏦Small Banks struggle
🏦NBFCs struggle barring one or two
(24/24)