
2/n
Fellow academics, when are we going to start fixing our urgent structural problems that strain family bonds and present ongoing barriers to diversifying our educational and scientific leadership? You wonder, what the heck is this guy talking about?
1/n
2/n
3/n
Teaching: 20h/w x 20w = 400h
Meetings of all sorts: 10h/w x 48w= 480h
Replying to email: 2h/d x 365d = 730h
Attending and giving talks: 2h/w x 50w = 100h
4/n
5/n
6/n
7/n
8/n
9/n
10/n
11/n
12/n
13/n
14/n
15/n
16/n
17/n
18/n
https://t.co/cMbIIRmlwi
19/n
20/n
21/n
22/n
23/n
More from Science

"NO LONGER BEST IN THE WORLD"
UNEP's new Human Development Index includes a new (separate) index: Planetary pressures-adjusted HDI (PHDI). News in Norway is that its position drops from #1 to #16 because of this, while Ireland rises from #2 to #1.
Why?
https://t.co/aVraIEzRfh
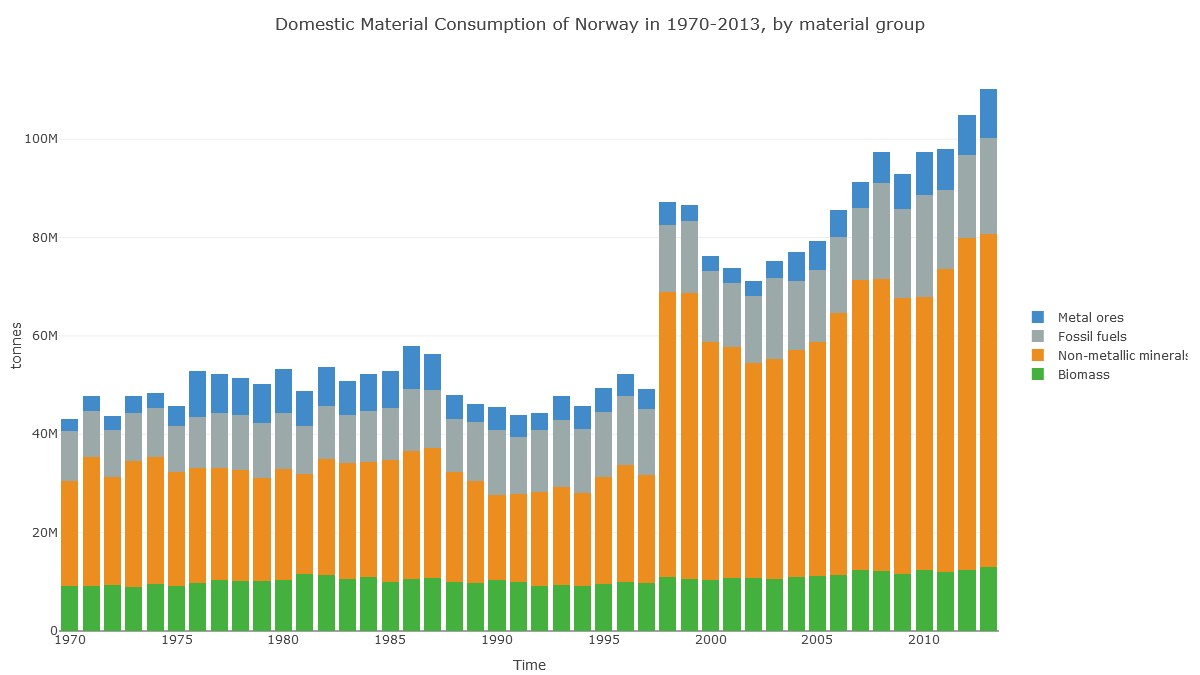
Check out Norway's 'Domestic Material Consumption'. Fossil fuels are no different here to Ireland's. What's different is this huge 'non-metallic minerals' category.
(Note also the jump in 1998, suggesting data problems.)
https://t.co/5QvzONbqmN
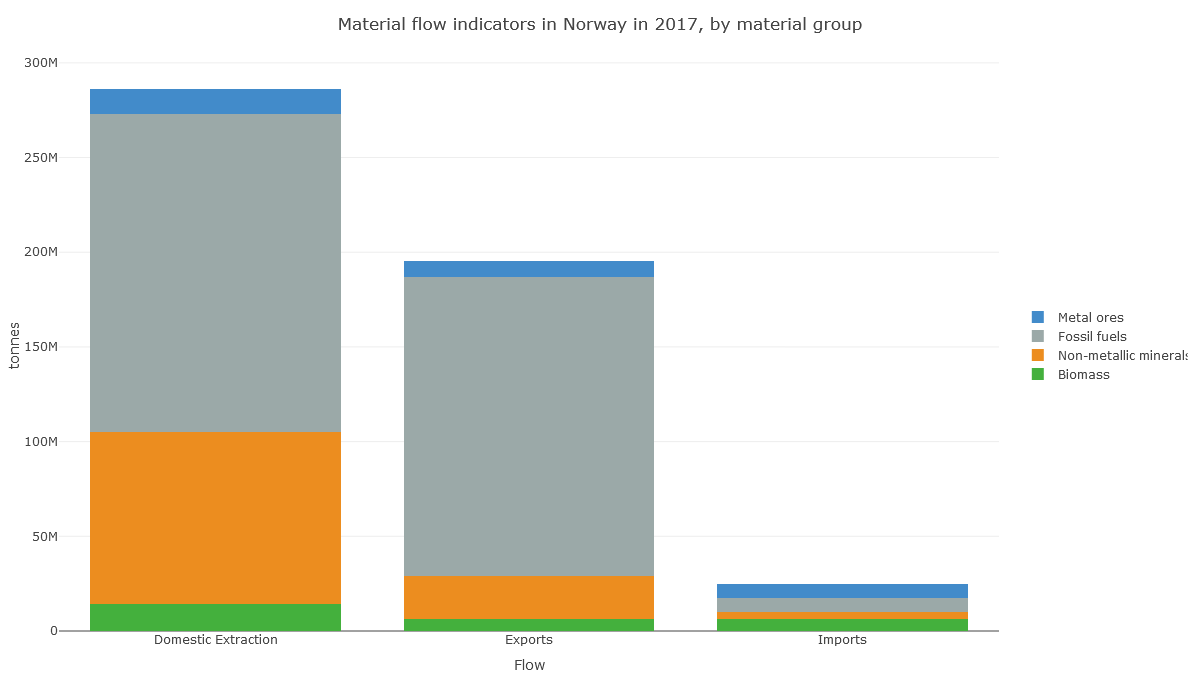
In Norway's case, it looks like the apparent consumption equation (production+imports-exports) for non-metal minerals is dominated by production: extraction of material in Norway.
https://t.co/5QvzONbqmN
And here we see that this production of non-metallic minerals is sand, gravel and crushed rock for construction. So it's about Norway's geology.
https://t.co/y6rqWmFVWc
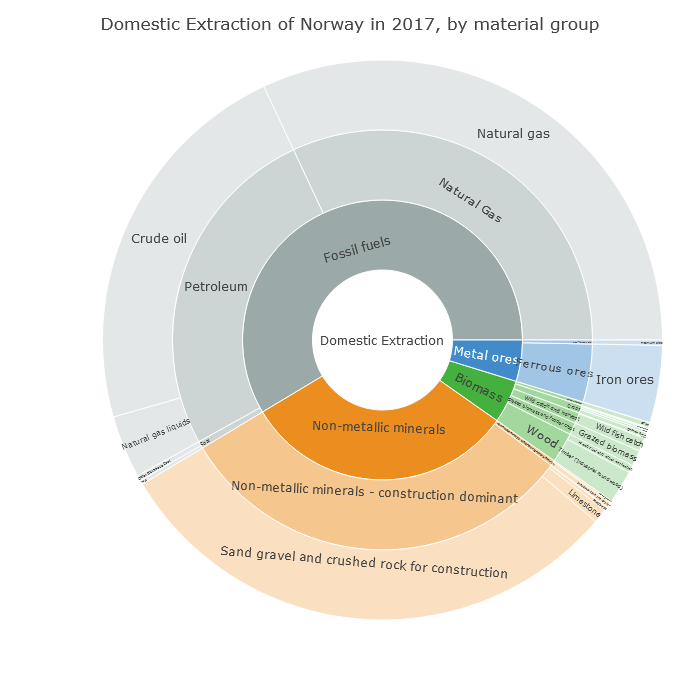
Norway drops 15 places on the PHDI list not because of its CO₂ emissions (fairly high at 41st highest in the world per capita), but because of its geology, because it shifts a lot of rock whenever it builds anything.
UNEP's new Human Development Index includes a new (separate) index: Planetary pressures-adjusted HDI (PHDI). News in Norway is that its position drops from #1 to #16 because of this, while Ireland rises from #2 to #1.
Why?
https://t.co/aVraIEzRfh
Check out Norway's 'Domestic Material Consumption'. Fossil fuels are no different here to Ireland's. What's different is this huge 'non-metallic minerals' category.
(Note also the jump in 1998, suggesting data problems.)
https://t.co/5QvzONbqmN
In Norway's case, it looks like the apparent consumption equation (production+imports-exports) for non-metal minerals is dominated by production: extraction of material in Norway.
https://t.co/5QvzONbqmN
And here we see that this production of non-metallic minerals is sand, gravel and crushed rock for construction. So it's about Norway's geology.
https://t.co/y6rqWmFVWc
Norway drops 15 places on the PHDI list not because of its CO₂ emissions (fairly high at 41st highest in the world per capita), but because of its geology, because it shifts a lot of rock whenever it builds anything.

#DDDD $LBPS $LOAC
A thread on the potential near term catalysts behind why I have increased my position in 4d Pharma @4dpharmaplc (LON: #DDDD):

1) NASDAQ listing. This is the most obvious.
The idea behind this is that the huge pool of capital and institutional interest in the NASDAQ will enable a higher per-share valuation for #DDDD than was achievable in the UK.
Comparators to @4dpharmaplc #DDDD (market capitalisation £150m) on the NASDAQ and their market capitalisation:
Seres Therapeutics: $2.33bn = £1.72bn (has had a successful phase 3 C. difficile trial); from my previous research (below) the chance of #DDDD achieving this at least once is at least
Kaleido Biosciences: $347m = £256m. 4 products under consideration, compared to #DDDD's potential 16. When you view @4dpharmaplc's 1000+ patents and AI-driven MicroRx platform (not to mention their end-to-end manufacturing capability), 4d's undervaluation is clear.
A thread on the potential near term catalysts behind why I have increased my position in 4d Pharma @4dpharmaplc (LON: #DDDD):
1) NASDAQ listing. This is the most obvious.
The idea behind this is that the huge pool of capital and institutional interest in the NASDAQ will enable a higher per-share valuation for #DDDD than was achievable in the UK.
Comparators to @4dpharmaplc #DDDD (market capitalisation £150m) on the NASDAQ and their market capitalisation:
Seres Therapeutics: $2.33bn = £1.72bn (has had a successful phase 3 C. difficile trial); from my previous research (below) the chance of #DDDD achieving this at least once is at least
While looking at speculative pharmaceutical stocks I am reminded of why I am averse to these risky picks.#DDDD was compelling enough, though, to break this rule. The 10+ treatments under trial, industry-leading IP portfolio, and comparable undervaluation are inescapable.
— Shrey Srivastava (@BlogShrey) December 16, 2020
Kaleido Biosciences: $347m = £256m. 4 products under consideration, compared to #DDDD's potential 16. When you view @4dpharmaplc's 1000+ patents and AI-driven MicroRx platform (not to mention their end-to-end manufacturing capability), 4d's undervaluation is clear.


