Let's discuss how little you actually understand about economics and energy.
The first thing to understand is that energy is not globally fungible. Electricity decays as it leaves its point of origin; it’s expensive to transport. There is a huge excess (hydro) in many areas.
Let's discuss the environmental cost of bitcoin. Because despite all the push for sustainable and green investment in the tech sector, there's a giant smoldering Chernobyl sitting at the heart of Silicon Valley which a lot of investors would prefer you remain quiet about. \U0001f9f5 (1/)
— Stephen Diehl (@smdiehl) January 17, 2021
You wouldn't argue that we are producing *too much* electricity from renewables, right?
Many previous estimates have quite faulty methods and don't take into account the actual energy sources. Is it fair to put a GHG equivalent on hydro or solar power? That would seem a bit disingenuous, no?

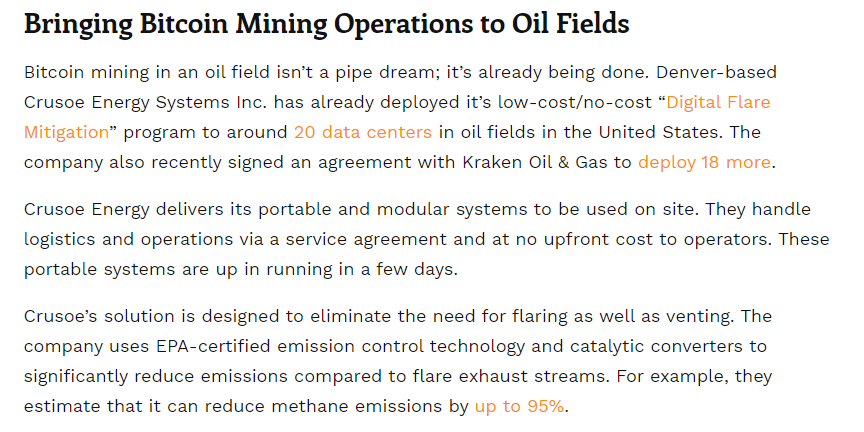
Recently the petro industry has experimented with burning CH4 "flare-offs" to power Bitcoin miners, cutting methane emissions and reducing warming potential.
https://t.co/WaleCRMh51
More from Economy


1/ Trend Factor: Any Economic Gains from Using Information over Investment Horizons? (Han, Zhou, Zhu)
"A trend factor using multiple time lengths outperforms ST reversal, momentum, and LT reversal, which are based on the three price trends separately."
https://t.co/udkvsdw2Lz
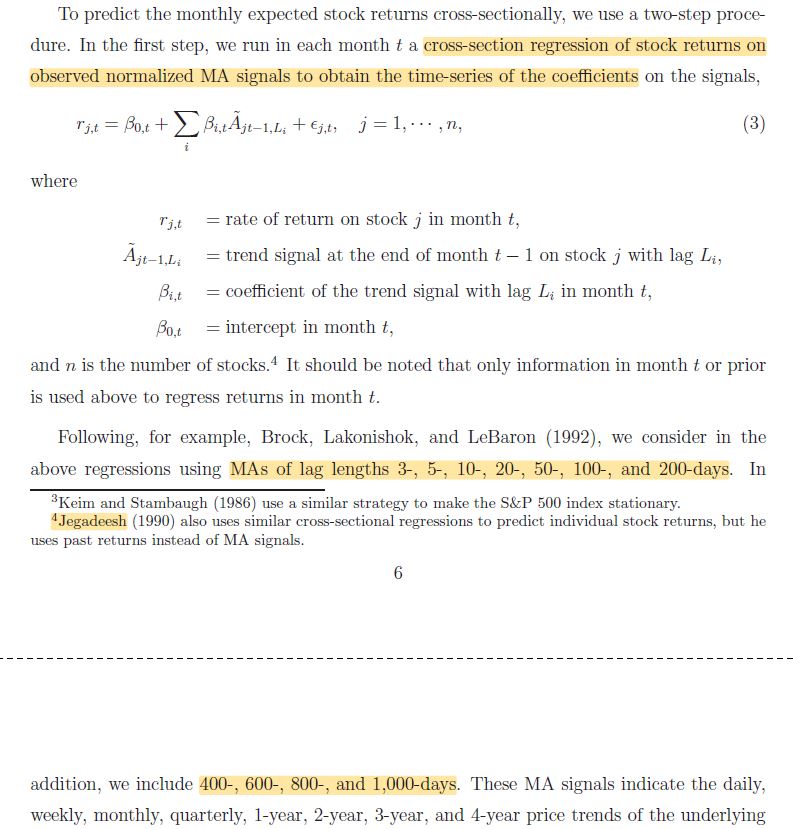
2/ This resembles combining multiple measures of ST reversal, momentum, and LT reversal (forecasts determined by walking forward rather than using signs from the full sample).
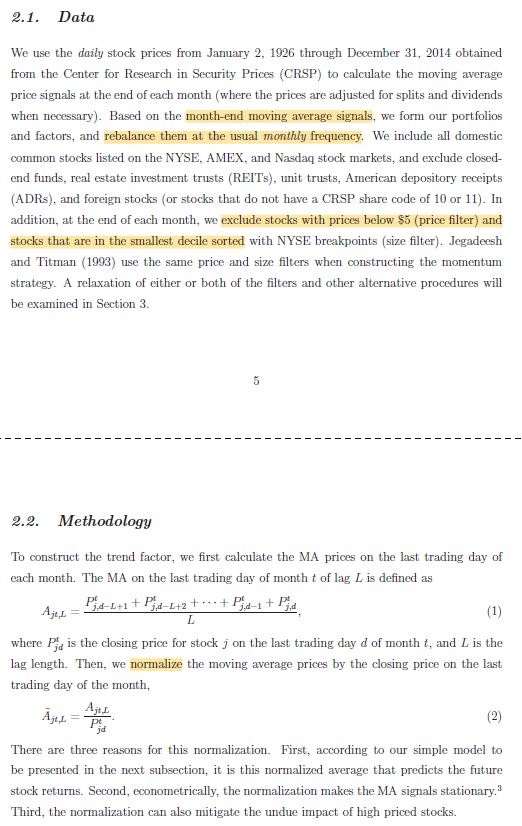
Unlike normal moving average signals, these are *cross-sectional.* More below:
https://t.co/wkIFLg9jtK
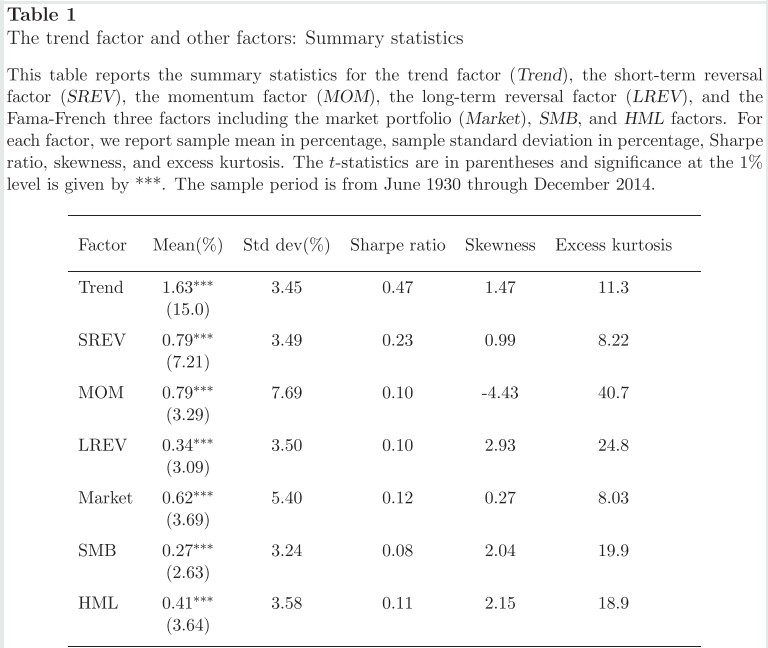
3/ Unsurprisingly, the Trend factor formed by this approach outperforms benchmarks in terms of both Sharpe ratio and tail metrics. It's combining momentum with two factors that are negatively correlated to it AND using multiple specifications.
More here:
https://t.co/x8Tloz3iyL
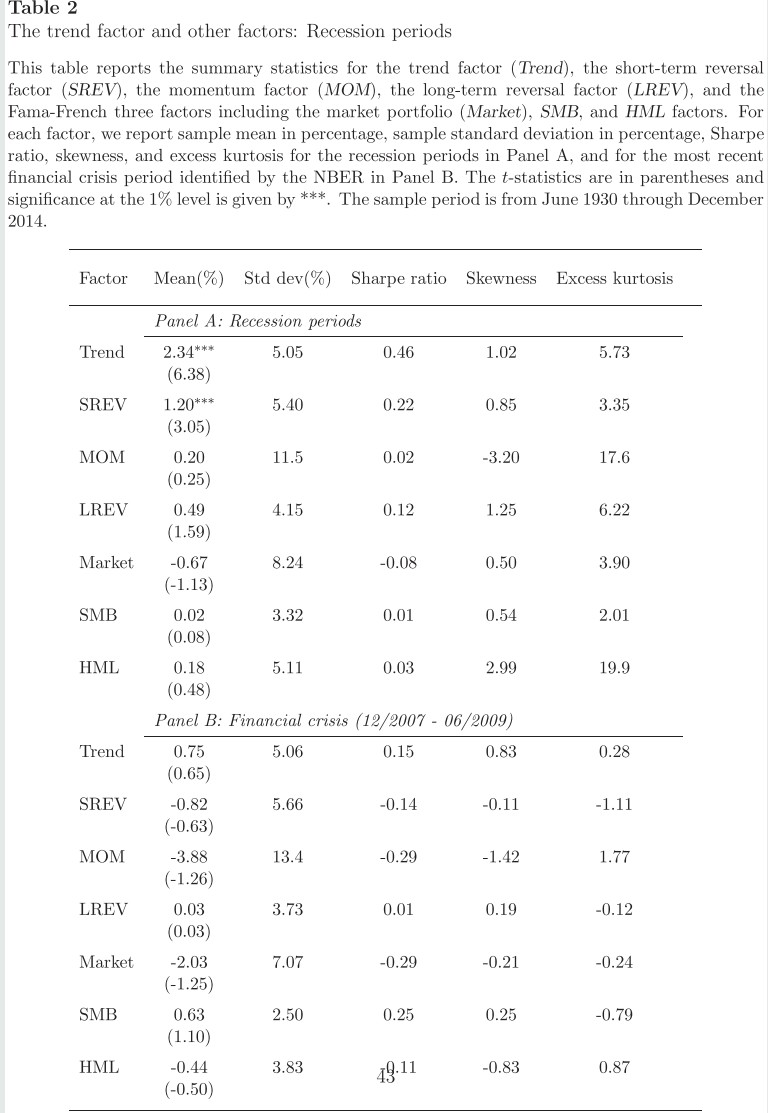
4/ "Average return and volatility of the trend factor are both higher in recession periods. However, the Sharpe ratio is virtually the same.
"Interestingly, all of the factors still have positive average returns.
"Momentum experiences the greatest increase in volatility."
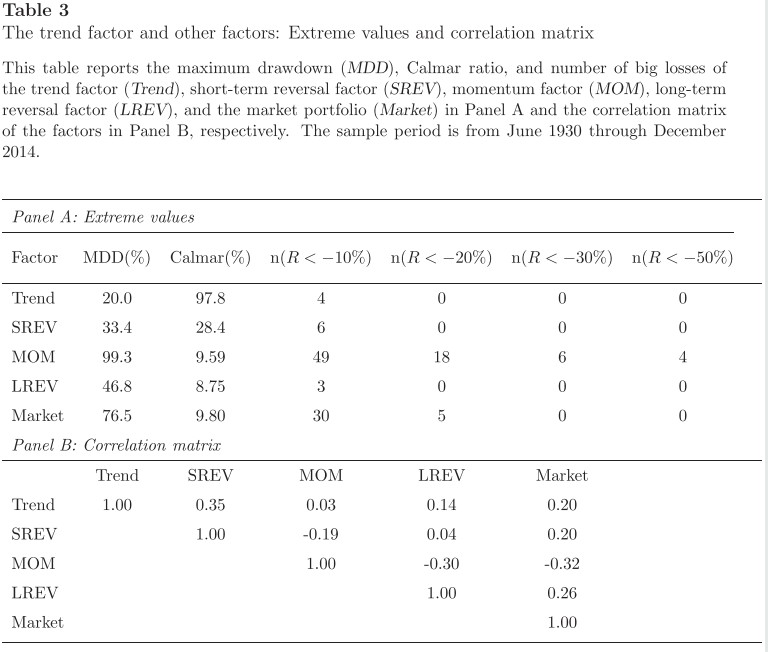
5/ "In terms of maximum drawdown and the Calmar ratio, the trend factor performs the best.
"The trend factor is correlated with the short-term reversal factor (35%), long-term reversal factor (14%), and the market (20%) but is virtually uncorrelated with the momentum factor."
"A trend factor using multiple time lengths outperforms ST reversal, momentum, and LT reversal, which are based on the three price trends separately."
https://t.co/udkvsdw2Lz
2/ This resembles combining multiple measures of ST reversal, momentum, and LT reversal (forecasts determined by walking forward rather than using signs from the full sample).
Unlike normal moving average signals, these are *cross-sectional.* More below:
https://t.co/wkIFLg9jtK
1/ Cross-Sectional and Time-Series Tests of Return Predictability: What Is the Difference? (Goyal, Jegadeesh)
— Darren \U0001f95a (@ReformedTrader) June 18, 2019
"The difference between the performances of TS and CS strategies is largely due to a time-varying net-long investment in risky assets."https://t.co/CSIn3ujN2R pic.twitter.com/XHnVmIart4
3/ Unsurprisingly, the Trend factor formed by this approach outperforms benchmarks in terms of both Sharpe ratio and tail metrics. It's combining momentum with two factors that are negatively correlated to it AND using multiple specifications.
More here:
https://t.co/x8Tloz3iyL
1/ An Executive Summary (in Tweet form) of our new paper
— Adam Butler (@GestaltU) March 27, 2019
Dual Momentum \u2013 A Craftsman\u2019s Perspective
Download here: https://t.co/Y9GlGNohBg
Everything that follows in this thread is based on HYPOTHETICAL AND SIMULATED RESULTS. pic.twitter.com/9m5YJnTdtq
4/ "Average return and volatility of the trend factor are both higher in recession periods. However, the Sharpe ratio is virtually the same.
"Interestingly, all of the factors still have positive average returns.
"Momentum experiences the greatest increase in volatility."
5/ "In terms of maximum drawdown and the Calmar ratio, the trend factor performs the best.
"The trend factor is correlated with the short-term reversal factor (35%), long-term reversal factor (14%), and the market (20%) but is virtually uncorrelated with the momentum factor."