2/n
Part 4: Understanding #OptionsBasic for #Nifty #BankNifty
In previous threads, we understood Intrinsic/Extrinsic value of options, how to achieve greek neutrality, risk management and how to define cheap or expensive options. Now
What Is Historical Volatility (HV)?
...1/n
2/n
3/n
For trending markets, historical volatility measures how far traded prices move away from a central average, or moving average, price.
4/n
...5/n
Implied volatility represents the expected volatility of a stock over the life of the option. As expectations change, option premiums react appropriately. Implied volatility is directly influenced by the supply and demand
6/n
share price's direction. As expectations rise, or as the demand for an option increases, implied volatility will rise. Options that have high levels of implied volatility will result in
...7/n
...8/n
So to BUY or SELL options
If HV>IV=buy options
If IV>HV=sell options
9/n
If IV > HV = sell options - We assume IV is high and will decrease and value of sold option will decrease.
It has to be used with direction.
10/n
https://t.co/CF9KbimgRI
https://t.co/PKd5Jwl5xq
You May Also Like


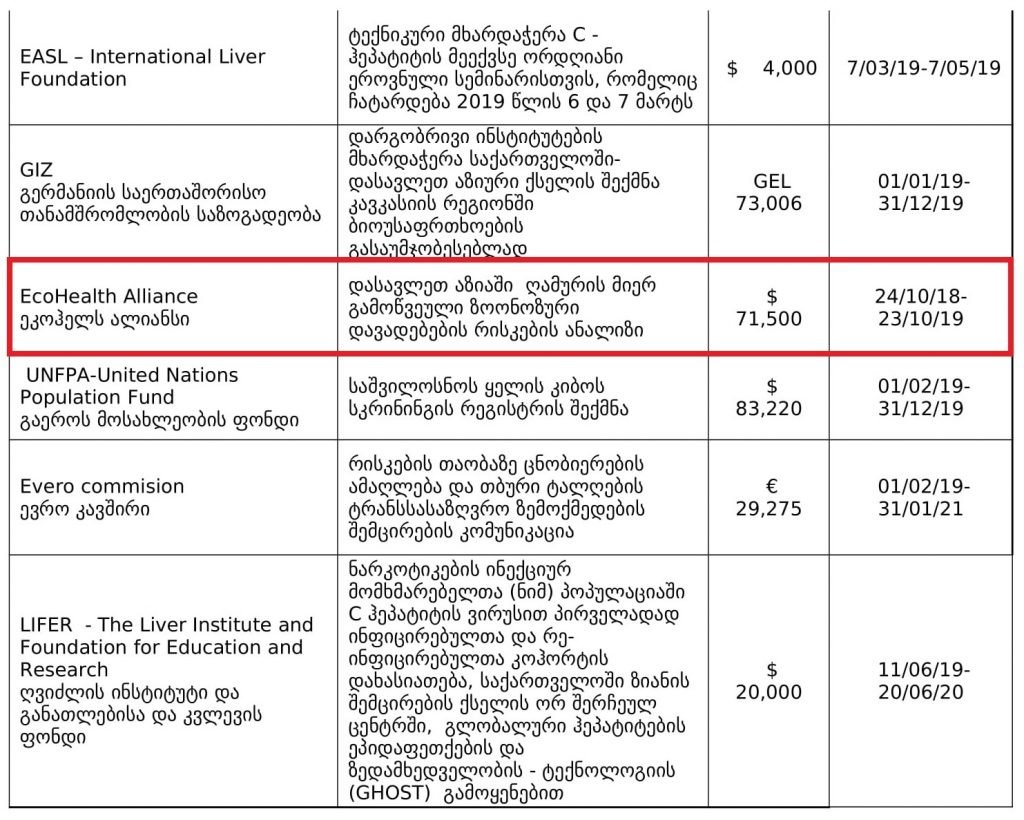
1. Project 1742 (EcoHealth/DTRA)
Risks of bat-borne zoonotic diseases in Western Asia
Duration: 24/10/2018-23 /10/2019
Funding: $71,500
@dgaytandzhieva
https://t.co/680CdD8uug
2. Bat Virus Database
Access to the database is limited only to those scientists participating in our ‘Bats and Coronaviruses’ project
Our intention is to eventually open up this database to the larger scientific community
https://t.co/mPn7b9HM48
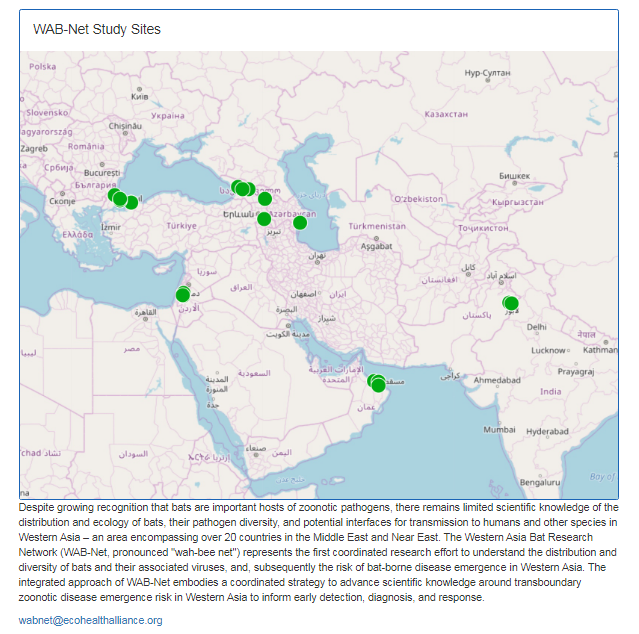
3. EcoHealth Alliance & DTRA Asking for Trouble
One Health research project focused on characterizing bat diversity, bat coronavirus diversity and the risk of bat-borne zoonotic disease emergence in the region.
https://t.co/u6aUeWBGEN
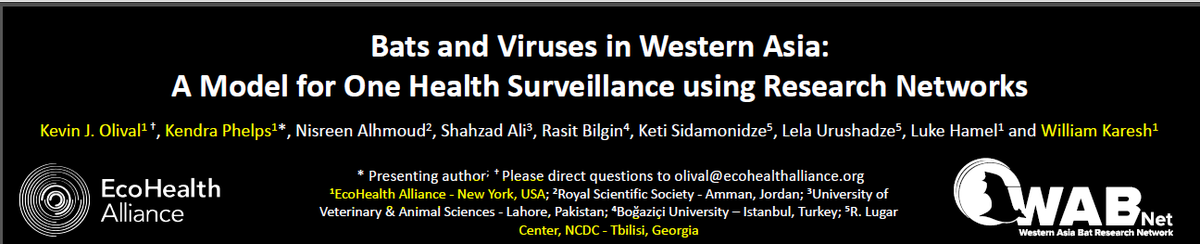
4. Phelps, Olival, Epstein, Karesh - EcoHealth/DTRA
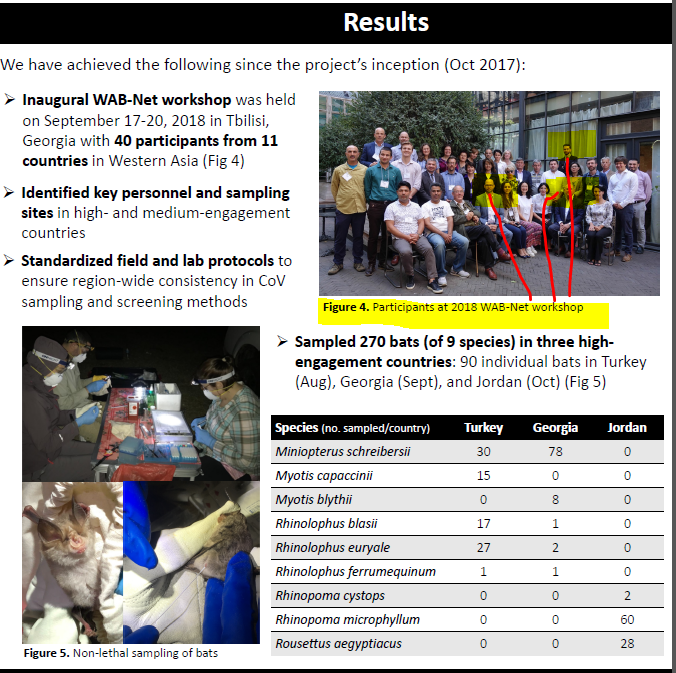
5, Methods and Expected Outcomes
(Unexpected Outcome = New Coronavirus Pandemic)
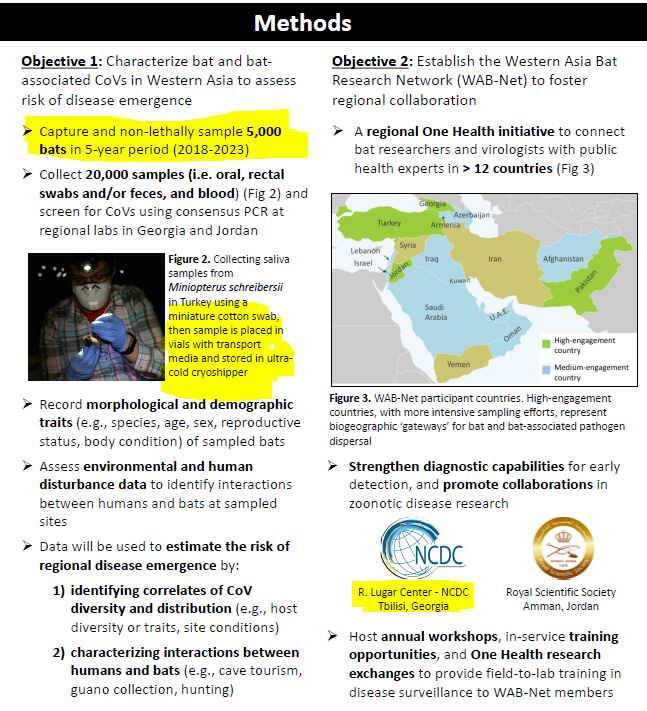
Risks of bat-borne zoonotic diseases in Western Asia
Duration: 24/10/2018-23 /10/2019
Funding: $71,500
@dgaytandzhieva
https://t.co/680CdD8uug
2. Bat Virus Database
Access to the database is limited only to those scientists participating in our ‘Bats and Coronaviruses’ project
Our intention is to eventually open up this database to the larger scientific community
https://t.co/mPn7b9HM48
3. EcoHealth Alliance & DTRA Asking for Trouble
One Health research project focused on characterizing bat diversity, bat coronavirus diversity and the risk of bat-borne zoonotic disease emergence in the region.
https://t.co/u6aUeWBGEN
4. Phelps, Olival, Epstein, Karesh - EcoHealth/DTRA
5, Methods and Expected Outcomes
(Unexpected Outcome = New Coronavirus Pandemic)